

What is the story about?
The Tata Sons board is weighing an alternative route to address the long-standing liquidity concerns of the Shapoorji Pallonji (SP) Group while retaining
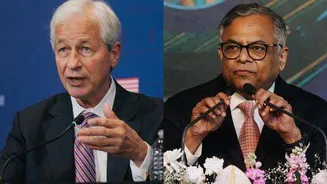
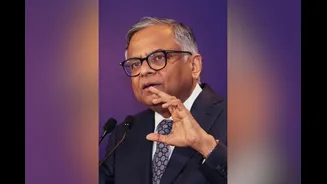
Tata Sons’ status as an unlisted company. Tata Sons Chairman Noel Tata has backed the decision to keep the group’s holding company unlisted while exploring mechanisms that could provide liquidity to the SP Group, which holds a significant stake in Tata Sons. The approach seeks to address two issues simultaneously: On one side is a Rs 25,000-crore-plus shareholder liquidity challenge involving the Shapoorji Pallonji Group. On the other is a fundamental Tata principle: keeping Tata Sons unlisted and preserving the ownership structure that has defined the group for generations.
Rs 25,000 Crore Liquidity Proposal:
At the Tata Sons Board meeting, Noel Tata stood by the decision not to list Tata Sons, while pushing for alternative lawful mechanisms to address the SP Group’s long-standing stake-related issue. The position follows the unanimous March 2024 decision, taken under Ratan Tata’s guidance, to retain Tata Sons as an unlisted company. The principal Tata Trusts reaffirmed that position in 2025.
But the significance of Noel Tata’s position lies in what came next.
Rather than simply rejecting a listing, he put forward a potential route to unlock liquidity for the SP Group.
The proposal envisages a transaction that could monetise part of the SP Group’s Tata Sons holding for at least Rs 25,000 crore through a two-tranche structure over 18 months. A selective capital reduction has also been proposed, subject to the required corporate, legal and regulatory processes.
Governance At The Centre Of Tata Sons Structure:
In parallel, Tata Sons could explore multiple funding avenues: from internal cash generation and monetisation of listed investments to bringing external investors into newer businesses.
The strategy effectively separates two questions that have often been viewed together: Does Tata Sons need to be listed to solve the shareholder issue? And can the SP Group’s liquidity requirement be addressed without changing Tata Sons’ fundamental structure? an analyst noted.
Noel Tata’s approach appears designed around the second proposition. And that puts governance at the centre of the story. The gold standard of governance, he added.
Its majority ownership rests with charitable trusts whose dividends support institutions and initiatives in healthcare, education, research and other public-purpose areas. That ownership architecture is central to the Tata model.
It also means that corporate governance at Tata Sons operates alongside a complex philanthropic and regulatory framework.
The tension became visible in May when an ex-parte direction from the Maharashtra Charity Commissioner required a Sir Ratan Tata Trust meeting to be deferred. Tata Trusts said subsequently that the direction was issued without prior notice or an opportunity for a hearing.
Listing Versus Alternative Route:
The SP Group has long sought a resolution around its investment in Tata Sons, while Tata Group entities have maintained their position on preserving the holding company's existing structure.
The proposed alternative would therefore attempt to address the liquidity issue without necessarily changing Tata Sons' unlisted status.
If the proposal moves ahead, the transaction would require the relevant corporate, legal and regulatory approvals. Its implementation would also determine how Tata Sons balances shareholder liquidity with its existing ownership and governance framework.
The developments place Tata Sons at the intersection of capital requirements, shareholder interests and institutional governance, with the outcome potentially shaping how the group manages similar structural challenges in the future.