

What's Happening?
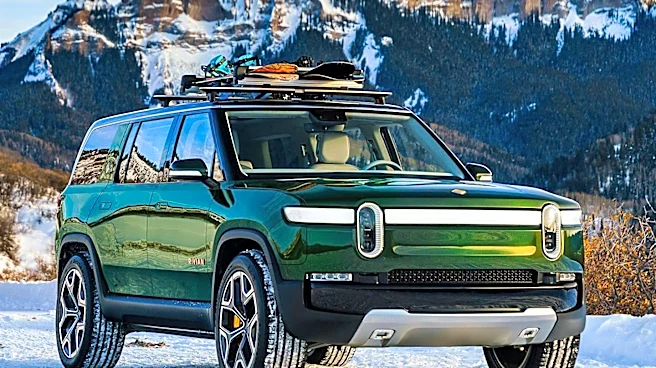
Rivian Automotive (NASDAQ: RIVN) has seen a substantial drop in its stock price, falling over 25% in the last three months, from $20 to just above $15. This decline comes despite the company reporting stronger-than-expected quarterly sales and an improved
adjusted per-unit financial performance. In the most recent quarter, Rivian delivered slightly over 12,000 vehicles and incurred a loss of $833 million. The company's R2 model, advertised with a base price of $44,990, launched with a higher price point of nearly $58,000, which analysts suggest was an 'unforced error' that gave competitors like Tesla's Model Y a head start. The U.S. EV market itself has experienced a downturn, with sales falling between 20% and 25% year-over-year, further contributing to investor caution regarding EV manufacturers.
Why It's Important?
The significant stock decline and ongoing unprofitability of Rivian highlight the intense challenges faced by emerging electric vehicle manufacturers in the U.S. market. Despite positive operational indicators like increased deliveries and improved per-unit financials, investor skepticism persists due to substantial losses and a competitive landscape dominated by established players like Tesla. The pricing strategy for the R2 model, launching at a higher price than initially advertised, could erode consumer trust and hinder market penetration, especially in a segment where affordability is becoming increasingly crucial. This situation reflects broader market concerns about the long-term viability of EV startups that are heavily reliant on capital-intensive manufacturing and technology development, while simultaneously navigating fluctuating consumer demand and high production costs. The performance of Rivian's stock serves as a bellwether for investor confidence in the broader EV sector's ability to achieve sustainable profitability.
What's Next?
Rivian's immediate future will likely involve intense scrutiny on its ability to scale production efficiently, reduce costs, and move towards profitability. The company's upcoming R3 and R4 models, which are expected to be priced 'materially lower' than the R2, will be critical in attracting a broader consumer base and improving sales volume. Rivian will need to demonstrate a clear path to profitability, potentially through increased economies of scale, further cost reductions in its supply chain, and continued innovation in software and services to differentiate its offerings. Investor sentiment will heavily depend on future earnings reports, delivery figures, and any strategic partnerships or funding rounds. The company's participation in industry forums, such as Evercore’s ADAS, AV & AI Forum, may provide updates on its technology roadmap, which could influence market perception, though no new financial targets are expected from such events.
Beyond the Headlines
The struggles of Rivian, despite its innovative product lineup and strong brand identity, underscore a deeper narrative about the maturation of the electric vehicle industry. The initial hype and high valuations for EV startups are giving way to a more pragmatic assessment of their financial sustainability. This shift highlights the immense capital requirements and operational complexities of automotive manufacturing, even for companies focused on cutting-edge technology. The market's reaction to Rivian's performance suggests that technological prowess alone is insufficient; a robust business model, efficient production, and a clear path to profitability are paramount. This scenario could lead to consolidation within the EV sector, with smaller, less capitalized companies struggling to compete. It also emphasizes the importance of strategic pricing and market positioning, as consumers become more discerning and the competitive landscape intensifies, pushing all players to deliver value beyond just electric propulsion.