
What's Happening?
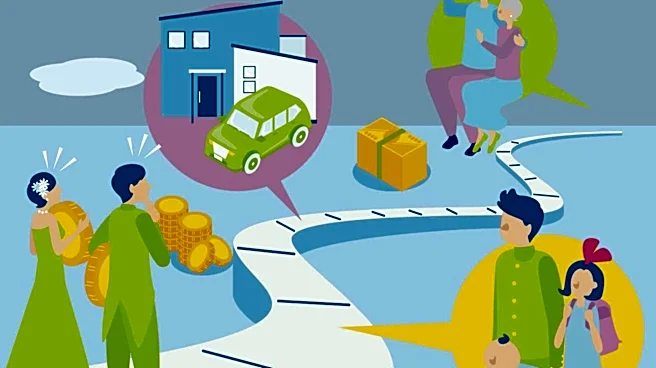
Retirement planning in one's 30s is identified as a critical decade for building financial momentum, even amidst numerous competing financial priorities such as buying a house, raising children, paying for childcare, and managing student loans. While
many may not have saved significantly in their 20s, starting in the 30s still provides decades for investments to grow. Financial experts recommend aiming to have one times an individual's annual income saved by age 30 and three times by age 40, typically by saving about 15% of pre-tax income annually, including employer contributions. Key strategies for this age group include reassessing existing retirement accounts, increasing contribution rates as income grows (especially with raises), and carefully balancing retirement savings with other major financial goals like homeownership and family expenses. It is advised to avoid raiding retirement accounts for other goals due to the significant opportunity cost of lost investment growth.
Why It's Important?
The 30s represent a pivotal period for retirement savings due to the power of compound interest; even small, consistent contributions made early can yield substantial returns over several decades. Neglecting retirement planning during this time can lead to significant shortfalls later in life, potentially forcing individuals to work longer or compromise their desired retirement lifestyle. Balancing immediate financial demands with long-term savings is a common challenge, and strategic decisions made in the 30s can set the trajectory for future financial independence. Prioritizing retirement savings, even over other seemingly urgent goals like children's college funds (as there are no 'loans for retirement'), ensures that individuals secure their own financial future, which ultimately benefits their families by preventing future financial dependency.
What's Next?
Individuals in their 30s should take proactive steps to review their financial situation, consolidate old 401(k)s, and increase their retirement contributions, particularly when receiving raises. Setting up automatic contribution increases can make this process seamless. Those juggling complex financial situations, such as stock compensation or starting a business, may benefit from consulting a fee-only, fiduciary financial advisor. The focus will be on maintaining a diversified portfolio, potentially through target-date funds or index funds, and avoiding overly conservative investment strategies too early. Continuous monitoring and adjustment of financial plans will be necessary to adapt to changing life circumstances and economic conditions, ensuring that retirement savings remain on track despite competing demands.
Beyond the Headlines
The challenges of retirement planning in the 30s reflect broader societal and economic shifts, including rising costs of living, student loan debt, and the increasing financial burden of raising a family. This era often marks a period of significant life transitions, where financial decisions have long-lasting consequences. The advice to prioritize one's own retirement over children's college funds, while pragmatic, highlights a tension between immediate family needs and long-term personal security. This underscores the need for comprehensive financial education and accessible advisory services to help young professionals navigate these complex choices. The emphasis on avoiding 'lifestyle creep' with raises also speaks to the psychological aspects of financial management, where discipline and foresight are crucial in a consumer-driven society to build lasting wealth.