
What's Happening?
The Carnegie Endowment for International Peace, through the insights of senior non-resident scholar Michael Pettis, is examining China's industrial overcapacity and its implications for the global economy. China's production in various sectors, including
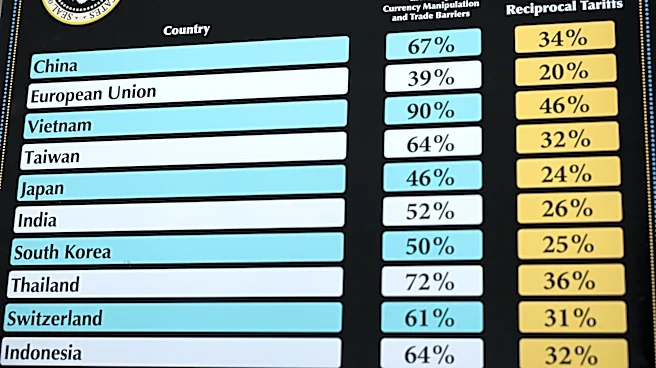
steel, automobiles, and high-tech goods, has outpaced its domestic demand, leading to a surge in exports. This phenomenon, termed 'China Shock 2.0,' differs from the earlier 'China Shock' of the 2000s by focusing on more technologically advanced and capital-intensive sectors like electric vehicles and batteries. Pettis argues that China's competitive edge is partly sustained by a model of high investment, cheap financing, and supportive industrial policies, allowing companies to operate and expand even with insufficient financial returns. This creates an imbalance where surplus production seeks international markets, putting pressure on manufacturers in other countries that lack similar financial and infrastructural advantages.
Why It's Important?
This situation is critical for the global economy, as China's industrial overcapacity can distort international markets, depress prices, and challenge the competitiveness of industries in other nations. For the U.S. and its allies, this could lead to increased trade tensions, calls for protectionist measures, and potential job losses in affected sectors. The shift from labor-intensive to capital and technology-intensive exports means that the impact is now felt in more advanced manufacturing sectors, posing a greater challenge to developed economies. The underlying issue, as highlighted by Pettis, is structural: China's economic model prioritizes production and investment over domestic consumption, creating a continuous need to export surpluses. This dynamic can hinder the industrial development of other countries, particularly those attempting to build higher value-added manufacturing capabilities.
What's Next?
Countries are likely to continue exploring and implementing various measures to address the influx of Chinese goods, including tariffs and trade defense instruments. However, as Pettis suggests, these measures may only offer temporary relief without addressing the root causes of China's overcapacity. The International Monetary Fund (IMF) has also noted China's weak domestic demand and prolonged real estate sector difficulties, advocating for a transition to a growth model driven more by household consumption. If China does not rebalance its economy towards greater domestic consumption, the pressure on global markets from its industrial output is expected to persist. This could lead to ongoing trade disputes and a re-evaluation of global supply chains as nations seek to protect their domestic industries and foster technological independence.
Beyond the Headlines
Beyond immediate trade implications, China's industrial model raises deeper questions about economic sustainability and global economic governance. The reliance on debt-financed investments and industrial policies that support production even when unprofitable can lead to financial vulnerabilities within China and export those imbalances globally. This challenges the traditional understanding of competitive markets, where efficiency and profitability are expected to drive production decisions. The long-term implications include potential de-industrialization in some countries, increased global economic interdependence with China, and a re-evaluation of multilateral trade rules designed to ensure fair competition. The ethical dimension also arises concerning the fairness of competition when state-backed policies enable companies to operate under conditions not available to their international counterparts.