

What's Happening?
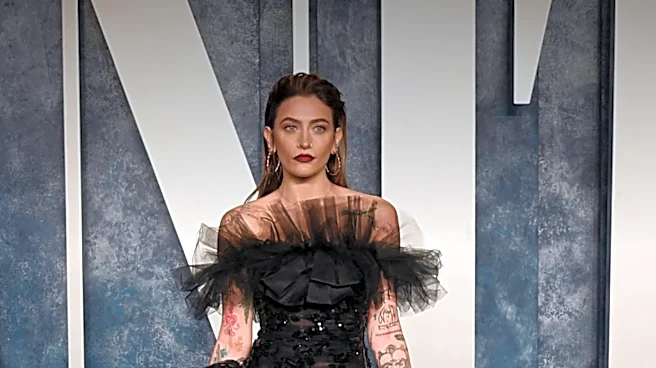
Paris Jackson, daughter of the late Michael Jackson, has petitioned a Los Angeles court to order a preliminary distribution of $600 million into the Michael Jackson Family Trust. She asserts that the trust remains unfunded more than 17 years after her
father's death in 2009, despite previous indications from executors in 2011 that a distribution was intended. According to her filing, an estate accounting showed approximately $850 million in cash and equivalents by the end of 2024. Paris argues that $600 million could be transferred while still retaining sufficient funds to cover outstanding liabilities. The estate, however, contends that unresolved litigation with the Internal Revenue Service (IRS) is a significant obstacle, citing an initial IRS claim of $700 million in taxes and penalties, which, though reduced, is still pending. The estate also refutes claims of withholding or reducing beneficiary payments, stating over $200 million has already been spent or distributed for their benefit. This dispute highlights a growing tension between Paris Jackson and the estate's executor, John Branca, regarding the management and distribution of Michael Jackson's substantial post-mortem earnings.
Why It's Important?
This legal challenge by Paris Jackson underscores the complexities and potential for conflict in managing high-profile celebrity estates, particularly when significant wealth is involved and family members have differing views on its administration. The outcome of this petition could set a precedent for how celebrity estates handle distributions to beneficiaries while facing ongoing legal and tax liabilities. For the Michael Jackson Estate, a favorable ruling for Paris could necessitate a substantial transfer of funds, potentially impacting its liquidity and future investment strategies. Conversely, if the court sides with the estate, it would reinforce the executors' authority in prioritizing legal and tax obligations over immediate trust funding. The dispute also brings to light the ongoing scrutiny of estate management fees and expenses, as Paris is challenging approximately $109 million in compensation for Branca, the late John McClain, and legal services, and seeks a reduction in the management-fee rate. This could influence how other celebrity estates structure their executive compensation and financial oversight.
What's Next?
A hearing is scheduled for December 4 to address Paris Jackson's request to move $600 million, or another amount deemed appropriate by the judge, into the family trust. The court will need to weigh the estate's claims regarding the unresolved IRS litigation against Paris's argument that a partial transfer is feasible and necessary to fulfill her father's intentions. This decision will determine the immediate financial future of the trust and could influence the timing of principal distributions to Michael Jackson's children as they reach specified ages (30, 35, and 40). Beyond the immediate financial implications, the ruling may also impact the ongoing family dynamics surrounding Michael Jackson's legacy, especially given Paris's public criticism of the recent 'Michael' biopic, despite her brother Prince serving as an executive producer. The outcome will likely shape future interactions between the beneficiaries and the estate's management.
Beyond the Headlines
The ongoing legal battle between Paris Jackson and the Michael Jackson Estate delves deeper than mere financial distribution; it touches upon the ethical responsibilities of estate executors and the interpretation of a deceased's wishes in the face of complex financial and legal realities. The estate's transformation from significant debt at Michael Jackson's death to generating billions highlights the immense value of intellectual property and brand management in the entertainment industry. However, the dispute also reveals the potential for tension when the financial success of an estate is perceived by beneficiaries as not directly translating into their intended inheritance. The challenge to management fees and expenses raises broader questions about transparency and accountability in estate administration, particularly for estates with vast and intricate financial structures. This case could contribute to evolving legal standards for fiduciary duties in celebrity estates, emphasizing the need for clear communication and alignment between executors and beneficiaries, especially when navigating long-term tax disputes and managing a global brand.