


What's Happening?
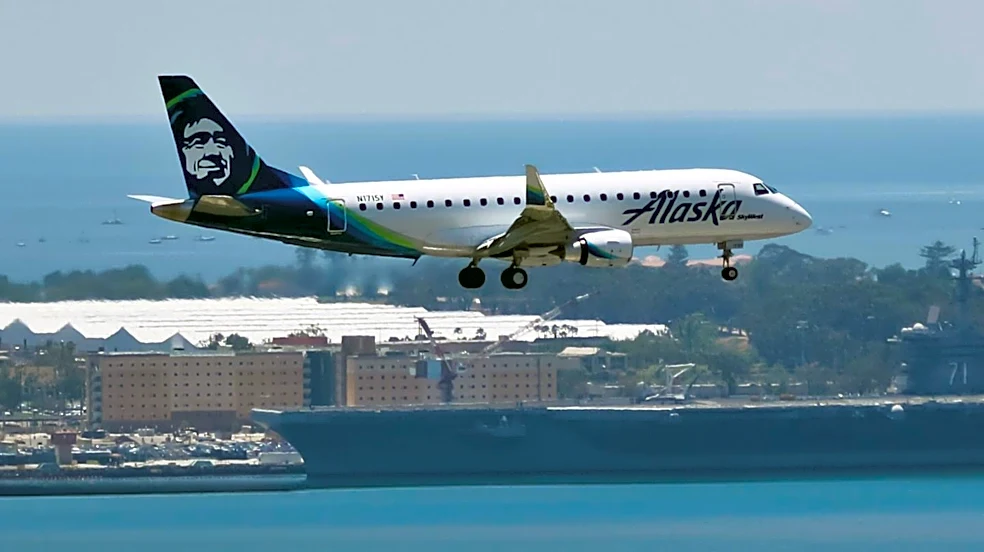
The Embraer E175 aircraft currently holds approximately 80% of the U.S. regional jet market, connecting numerous small communities to larger airline networks. This dominance is largely attributed to 'scope clauses' embedded in pilot agreements at major
U.S. airlines like American, Delta, and United. These clauses restrict partner airlines from operating aircraft under major brands to a maximum of 76 seats and a takeoff weight of 86,000 pounds (39,009 kg). The E175 fits within these limits, while Embraer's newer E2 version does not. Most U.S. airlines configure the E175 with 76 seats, typically 12 in first class and 64 in the main cabin, in a two-by-two layout. Airlines such as American Airlines (via Envoy Air), SkyWest Airlines, and Republic Airways utilize the E175 as a feeder aircraft from smaller airports to hubs, where larger narrow-body jets would be economically unfeasible. Numerical caps also apply, with United, for instance, limited to outsourcing no more than 255 aircraft with 51 to 76 seats, and American's regional jets over 65 seats capped at 40% of its narrow-body fleet. These limits have remained largely unchanged since 2012, despite pilot contract updates in 2023. Competing regional jet programs have been canceled, leaving the E175 as the primary compliant option.
Why It's Important?
The continued dominance of the Embraer E175 in the U.S. regional jet market has significant implications for airline operations, aircraft manufacturing, and regional connectivity. The restrictive scope clauses, while designed to protect pilot jobs and maintain a certain fleet structure, effectively create a barrier to entry for newer, more fuel-efficient aircraft like the Embraer E175-E2. This situation forces U.S. airlines to continue operating an older generation of aircraft, potentially impacting fuel efficiency, maintenance costs, and passenger comfort in the long run. For Embraer, the inability to sell its E2 model to its largest market has led to a prolonged development pause, pushing its potential entry into service to 2029 or later. This not only affects Embraer's revenue and market share but also stifles innovation in the regional jet segment. Furthermore, the lack of viable alternatives means that regional airlines and the communities they serve remain reliant on a single aircraft type, which could pose risks to service continuity and fleet modernization efforts.
What's Next?
The future of regional jet operations in the U.S. largely hinges on potential changes to the existing scope clauses in pilot agreements. Without modifications to these clauses, the Embraer E175 is expected to maintain its dominant position, and the E175-E2 will remain unviable for U.S. carriers. Any restart or entry into service for the E175-E2 is delayed until at least 2029, indicating that Embraer is not anticipating immediate changes. Airlines will likely continue to place orders for the current E175 model, as American Airlines did recently with an order for 90 E175s and options for 43 more. This trend suggests that U.S. regional air travel will continue to be served by the current generation of aircraft for the foreseeable future. Stakeholders, including pilot unions, airlines, and aircraft manufacturers, will need to engage in future negotiations to address the balance between pilot contract protections and the need for fleet modernization and efficiency.
Beyond the Headlines
The situation with the Embraer E175 and scope clauses highlights a broader tension between labor agreements, technological advancement, and market dynamics within the U.S. aviation industry. While scope clauses were initially established to prevent the outsourcing of mainline flying to lower-cost regional carriers, their current rigidity inadvertently creates a bottleneck for the adoption of more advanced aircraft. This can lead to a competitive disadvantage for U.S. airlines compared to international carriers that may have more flexibility in fleet composition. The long-term implications could include slower progress in reducing aviation's environmental footprint due to the continued use of less fuel-efficient aircraft, and potentially higher operating costs for regional airlines, which could impact ticket prices or service to smaller communities. The issue also underscores the complex interplay between collective bargaining, regulatory frameworks, and the global aerospace manufacturing landscape, where decisions made in one sector can have ripple effects across the entire industry.