

What's Happening?
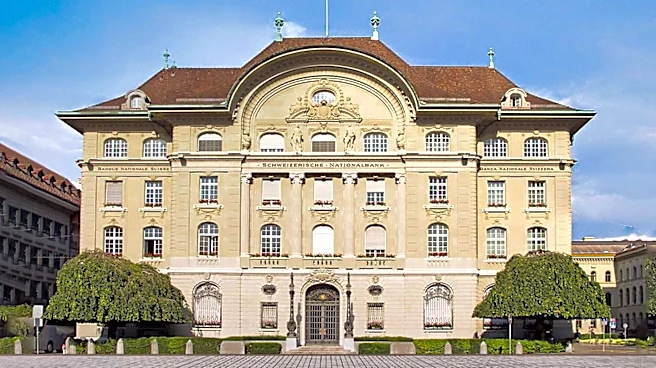
The Swiss National Bank (SNB), Switzerland’s central bank, has issued a warning that stablecoins possess the potential to disrupt the effectiveness of monetary policy. According to SNB Governing Board member Petra Tschudin, this technology could diminish
the central bank's capacity to influence borrowing costs and manage financial conditions. Stablecoins are digital assets designed to maintain a stable value by being pegged to a reference asset, such as the U.S. dollar or gold. Tschudin emphasized that while the SNB supports innovation, each new development requires assessment for its potential impact and the identification of necessary regulations. Risks are projected to escalate if stablecoins achieve widespread adoption and become increasingly detached from the traditional financial system that links central banks with commercial banks. The SNB is also scrutinizing the implications of stablecoins on central bank money, which serves as a risk-free payment method for interbank transactions. Since stablecoins operate outside the central banking system, a Swiss franc-denominated stablecoin's value is not automatically equivalent to a Swiss franc issued by the central bank, potentially undermining the principle of uniform monetary value across different locations.
Why It's Important?
The SNB's concerns highlight a significant potential challenge to traditional monetary policy mechanisms, which could have ripple effects on global financial stability, including in the U.S. If individuals and companies shift substantial funds from commercial banks into stablecoins, it could reduce the capital available for banks to lend. This reduction in lending capacity could directly impact interest rates and diminish the effectiveness of central bank policy rate changes in influencing borrowing costs across the broader economy. For the U.S., where the dollar is a primary peg for many stablecoins, such a scenario could complicate the Federal Reserve's efforts to manage inflation, stimulate economic growth, or respond to financial crises. A less effective monetary policy could lead to greater economic volatility and uncertainty, affecting businesses' investment decisions and consumers' purchasing power. The warning underscores the need for international cooperation and regulatory frameworks to address the systemic risks posed by the growing stablecoin market, ensuring that financial innovation does not inadvertently destabilize established economic controls.
What's Next?
The SNB's warning suggests that central banks globally, including the U.S. Federal Reserve, will likely intensify their scrutiny of stablecoins and their potential impact on monetary policy. This could lead to increased calls for comprehensive regulatory frameworks to govern stablecoin issuance, reserves, and operational standards. Policymakers may explore measures to integrate stablecoins more closely into the existing financial system or to develop new tools to counteract their potential disruptive effects. Discussions around central bank digital currencies (CBDCs) might also gain momentum as a potential response to maintain central bank control over the money supply in a digitalized economy. Financial institutions and businesses involved in stablecoin transactions may face evolving compliance requirements and increased oversight. The ongoing assessment of stablecoins' impact will likely involve collaboration between central banks, financial regulators, and international bodies to develop harmonized approaches to manage the risks while fostering responsible innovation in the digital asset space.
Beyond the Headlines
The SNB's statement delves into the fundamental nature of money and central bank authority in an increasingly digital world. The potential for stablecoins to operate outside the central banking system challenges the long-standing principle that a nation's currency should have a consistent value and be controlled by its central bank. This raises profound questions about financial sovereignty and the ability of governments to manage their economies. If stablecoins become a dominant form of transaction, they could fragment the monetary system, making it harder for central banks to implement macroeconomic policies effectively. This could lead to a loss of control over inflation, interest rates, and overall financial stability. The debate extends beyond mere regulation to the very definition of money and the role of central banks in maintaining economic order. The long-term implications could include a re-evaluation of the global financial architecture, potentially leading to new forms of digital currency governance or a significant shift in how monetary policy is conducted worldwide.