

What's Happening?
T. Rowe Price, a global investment manager overseeing $1.9 trillion, has begun utilizing custom-made models to protect its $165 billion emerging-market debt and equities portfolio from the anticipated effects of El Niño. This initiative stems from a multi-year
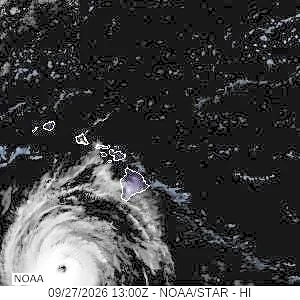
research partnership with Johns Hopkins University (JHU), which developed a suite of climate and weather analytics. Aaron Gifford, associate director of research for global sovereigns at T. Rowe Price, indicated that planning for this strategy began during the formation of the last El Niño. The climate phenomenon, characterized by warming across the equatorial Pacific Ocean, is already disrupting global weather patterns, impacting agricultural output in regions like Honduras, El Salvador, and Asia. T. Rowe Price's approach involves integrating these scientific insights into its proprietary macroeconomic forecasting models for emerging markets, aiming to mitigate potential losses and identify investment opportunities arising from El Niño's influence.
Why It's Important?
This proactive measure by T. Rowe Price highlights a growing trend among asset managers to incorporate climate change and specific weather phenomena like El Niño into their investment strategies. The financial implications of El Niño are significant, affecting everything from agricultural prices and energy supplies to government deficits and inflation in highly exposed emerging markets. By using advanced models, T. Rowe Price aims to gain a competitive edge in understanding and reacting to these complex interdependencies. This strategy is crucial for protecting its substantial emerging-market portfolio and could influence how other large investment firms approach climate-related risks. The collaboration with academic institutions like JHU also underscores the increasing demand for rigorous, data-driven analysis to navigate the evolving landscape of climate-induced financial volatility, potentially setting a new standard for risk management in the investment sector.
What's Next?
T. Rowe Price plans to continue refining and applying these models to guide investment decisions and potentially inform climate resilience-related clauses in lending agreements, particularly for small island nations. The research, which provides estimates of El Niño’s impact on temperature, precipitation, hydrology, and agriculture in 12 emerging markets across Latin America, Africa, and Asia, will be accessible to both bond analysts and stock pickers within the firm. The firm's head of emerging markets in fixed-income, Samy Muaddi, noted that this research will position T. Rowe Price to be ahead of the market in understanding the value embedded in climate-resilient debt clauses. Other asset managers, such as Moreton Capital Partners, are also targeting significant investments to capitalize on the anticipated shifts in food prices due to El Niño, indicating a broader industry movement towards integrating climate risk into financial forecasting and strategy.
Beyond the Headlines
The integration of climate and weather analytics into investment strategies, as demonstrated by T. Rowe Price, signifies a deeper shift in how financial institutions perceive and manage systemic risks. This goes beyond traditional economic indicators, acknowledging that environmental factors can have profound and far-reaching economic consequences. The partnership with Johns Hopkins University also highlights the increasing interdisciplinary collaboration between academia and the financial sector, fostering a more scientifically informed approach to investment. This trend could lead to the development of new financial products and risk assessment tools that explicitly account for climate variability, potentially influencing regulatory frameworks and corporate sustainability reporting. Furthermore, by considering climate resilience in debt clauses, T. Rowe Price is subtly promoting more sustainable practices in vulnerable nations, intertwining financial stability with environmental stewardship on a global scale.