

What's Happening?
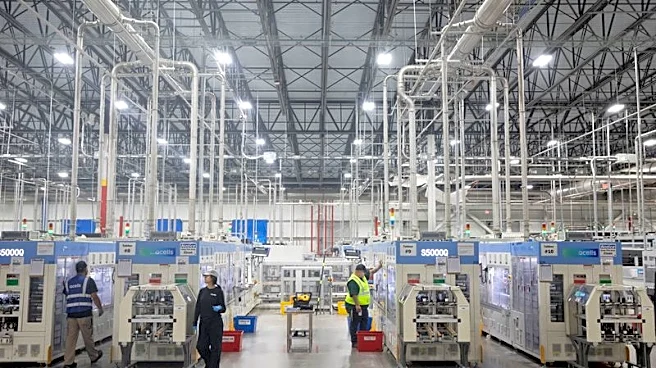
The semiconductor industry is experiencing significant bottlenecks in its equipment supply chain, despite massive investments in chips and fabrication plants driven by surging AI demand. Lead times for critical components needed to build semiconductor manufacturing
equipment have extended dramatically, with some laser equipment components reportedly taking up to 40 months to arrive. Other components, such as deposition components, now have lead times of 4 to 10 months, and packaging components range from 4 to over 6 months. This has resulted in major equipment lead times becoming 1.5 to 2 times longer than usual. The issue is shifting from merely fab capacity to the ability of the entire equipment supply chain to keep pace with the unprecedented demand. Component suppliers face a dilemma: while AI demand is high, the uncertainty of its long-term duration makes major capacity investments difficult. Geopolitical factors further complicate alternative sourcing strategies.
Why It's Important?
This bottleneck in the semiconductor equipment supply chain poses a significant threat to the U.S.'s efforts to boost domestic chip manufacturing and maintain its technological leadership in AI. Delays in acquiring essential equipment mean that new fabrication plants and expansions, including those supported by U.S. government initiatives, will take longer to come online, potentially slowing down the production of critical AI chips. This could impact the competitiveness of U.S. tech companies, increase costs, and create vulnerabilities in the supply chain for various industries reliant on advanced semiconductors. The extended lead times also highlight the intricate global interdependencies of the semiconductor ecosystem, where a delay in one part of the chain can have cascading effects worldwide. For U.S. policymakers, this situation underscores the need for strategies that not only incentivize chip production but also strengthen the entire manufacturing equipment supply chain, potentially through domestic production or diversified international partnerships.
What's Next?
The semiconductor industry will likely intensify efforts to de-risk and diversify its equipment supply chain. This could involve exploring new suppliers, investing in domestic manufacturing of critical components, and fostering greater collaboration between equipment manufacturers and their component providers. Companies may also seek to optimize their inventory management and forecasting to better anticipate demand fluctuations. Policymakers in the U.S. might consider new incentives or regulations aimed at strengthening the domestic supply chain for semiconductor manufacturing equipment, similar to existing efforts for chip production. The uncertainty surrounding the long-term duration of the AI demand surge will continue to influence investment decisions by component suppliers, potentially leading to a cautious approach to capacity expansion. Geopolitical considerations will also play a crucial role, as countries aim to secure their access to essential manufacturing capabilities.
Beyond the Headlines
The current bottlenecks in the semiconductor equipment supply chain reveal a deeper systemic challenge: the inherent fragility of highly specialized, globally distributed manufacturing networks. This situation highlights the tension between efficiency-driven globalization and the growing imperative for national security and supply chain resilience. The ethical implications include potential labor exploitation in efforts to speed up production, and environmental concerns related to increased resource extraction and waste generation from accelerated manufacturing. Culturally, it underscores the critical role of highly skilled labor and specialized knowledge in maintaining technological advancement, emphasizing the need for robust educational and training pipelines. In the long term, this could trigger a fundamental re-evaluation of industrial policy, moving towards more localized or regionally integrated supply chains for strategic technologies, even if it entails higher costs, to ensure stability and reduce geopolitical risks.