
What's Happening?
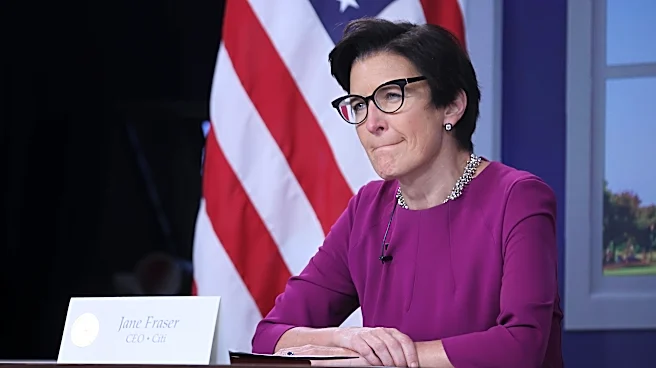
Citigroup announced its third-quarter 2026 earnings, reporting an earnings per share of $2.85, which surpassed the Zacks Consensus Estimate of $2.66. This marks an increase from $2.24 in the prior-year quarter. The company's net income for the quarter reached
$5.25 billion, a significant 39.8% rise compared to the same period last year. Revenues, net of interest expenses, were $23.85 billion, up 7.9% year-over-year, representing Citigroup's highest third-quarter revenues in a decade and exceeding the Zacks Consensus Estimate of $23.66 billion. This growth was primarily driven by a 13.7% increase in Net Interest Income (NII) to $16.98 billion, fueled by strong performance in Markets, Services, Wealth, and U.S. Consumer Cards. Operating expenses saw a 2.4% decline to $13.95 billion, largely due to the absence of a prior-year Banamex goodwill impairment charge and reduced professional services expenses, despite increases in transactional and product servicing costs, deposit insurance expenses, and compensation. The efficiency ratio improved to 58.5% from 64.7% year-over-year, indicating enhanced profitability.
Why It's Important?
Citigroup's robust third-quarter performance is significant for the U.S. financial sector, demonstrating resilience and growth in a competitive market. The substantial increase in net interest income highlights the bank's ability to capitalize on its core lending and financial services, benefiting from favorable market conditions. The improvement in the efficiency ratio suggests effective cost management and operational streamlining, which can lead to sustained profitability and investor confidence. For investors, the 1.6% stock increase since the last earnings report indicates a positive market reaction, and the company's trading at a discount compared to the industry could signal an attractive investment opportunity. The strong segmental performance across Services, Markets, Banking, and Wealth segments underscores a diversified and healthy business model, reducing reliance on any single revenue stream. This financial health can translate into increased lending capacity, supporting economic activity and potentially influencing broader market trends.
What's Next?
Following this strong earnings report, Citigroup is likely to continue its strategic focus on optimizing its core businesses and managing operational costs. The company's sustained growth in key segments like Services, Markets, and Wealth suggests ongoing investment and expansion in these areas. Investors will be closely watching for further details on how Citigroup plans to maintain its positive momentum, particularly in managing credit loss provisions and fee income, which were noted as offsetting factors in the recent quarter. The company's ability to sustain its improved efficiency ratio and continue growing its net interest income will be crucial for future performance. Any further announcements regarding strategic initiatives or capital allocation will be key indicators for the market and stakeholders.
Beyond the Headlines
Citigroup's strong financial results extend beyond immediate profitability, reflecting broader trends in the U.S. banking industry. The emphasis on higher net interest income suggests that banks are successfully navigating the current interest rate environment, potentially indicating a period of sustained profitability for the sector. The decline in non-accrual loans and the reduction in the total allowance for credit losses point to an improving credit quality landscape, which could signal a healthier economic environment for borrowers and lenders alike. This positive trend in credit quality could encourage more aggressive lending and investment, further stimulating economic growth. The company's ability to achieve its highest third-quarter revenues in a decade also highlights its adaptability and strategic positioning in a dynamic financial market, potentially setting a benchmark for other large financial institutions.