


What's Happening?
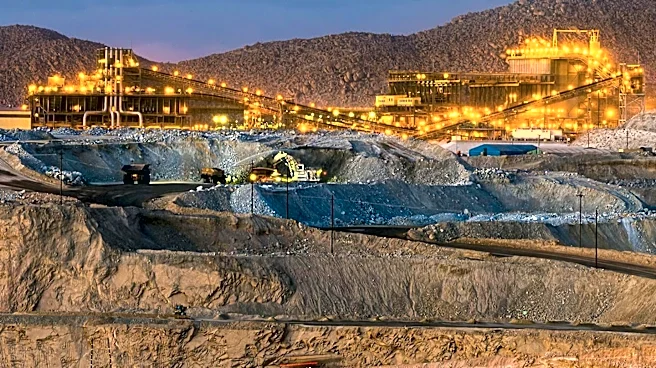
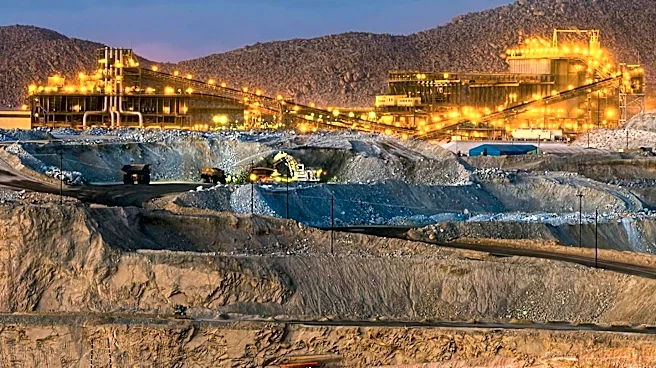
Chile, a major global source of mined copper, has experienced a downgrade in its production outlook and an unusually weak third quarter, according to industry reports. This reduction in availability is impacting concentrate purchasing and smelter planning
beyond Chile's borders. Despite this, copper prices have risen above $14,300 per metric ton, creating a contradiction with a substantial increase in exchange inventories. The Shanghai Metals Market reported an overnight LME copper closing price of $14,325.50 per ton, a 1.38% increase. This price surge is occurring even as LME-registered copper inventories reached 293,775 tons, their highest since mid-July, following significant deliveries into New Orleans. The immediate market focus is on where the tightness in copper supply truly lies: at the mines, among smelters, or within specific delivery regions, as rising prices coexist with increased metal entering exchange warehouses.
Why It's Important?
The situation in Chile is critical for the global copper market, as reduced supply from the world's largest producer can significantly influence international prices and availability. The divergence between rising copper prices and increasing inventories suggests a market driven more by concerns over future supply than by immediate demand. This dynamic affects various stakeholders, including mining companies, smelters, and manufacturers reliant on copper. While mines might benefit from higher realized prices, those experiencing lower output could see reduced profits due to fewer tons sold and higher unit costs. Smelters, facing tighter concentrate availability but rising refined inventories, could experience pressure on processing economics. This scenario highlights the complex interplay of supply chain disruptions, inventory levels, and market sentiment in determining commodity prices, with potential ripple effects across industries that use copper, from electronics to construction.
What's Next?
The market will closely monitor physical premiums, fabricator orders, and the direction of surveyed inventories in China to determine if buyers are accepting current prices or continuing to purchase only essential quantities. Further deliveries into New Orleans warehouses will also be watched, though these may not indicate ample supply in other regions due to logistical factors. For Chile, upcoming production updates and revised operating guidance will be crucial in distinguishing temporary operational setbacks from more persistent constraints that could extend into the coming months. The central bank's preliminary third-quarter GDP report, due on November 18, will provide further insights into the broader economic impact of the mining sector's performance. The long-term investment cycle, driven by electrification and green technologies, continues to project significant copper demand growth, but short-term market dynamics will dictate immediate price and supply trends.
Beyond the Headlines
The current copper market scenario in Chile underscores the vulnerability of global supply chains to localized production issues, even in the face of seemingly ample inventories. This situation could accelerate efforts by industries to diversify their sourcing or invest in recycling technologies to mitigate future supply risks. The emphasis on 'physical premiums' and 'warehouse geography' highlights the importance of granular market data beyond headline prices, revealing the complexities of commodity distribution and regional supply-demand imbalances. Furthermore, the contrast between Chile's mining struggles and the broader economic growth outside mining points to the need for economic diversification in resource-dependent nations. This event also serves as a reminder that long-term demand projections, such as those for electrification and electric vehicles, do not always align with short-term market behaviors, as buyers may exercise restraint when prices are elevated, impacting immediate demand signals.