

What's Happening?
Customers of major U.S. banks, including Chase, Bank of America, Capital One, and Wells Fargo, reported widespread outages on Monday. Downdetector.com indicated nearly 5,000 reports for Chase and approximately 1,400 for Bank of America and Wells Fargo combined.
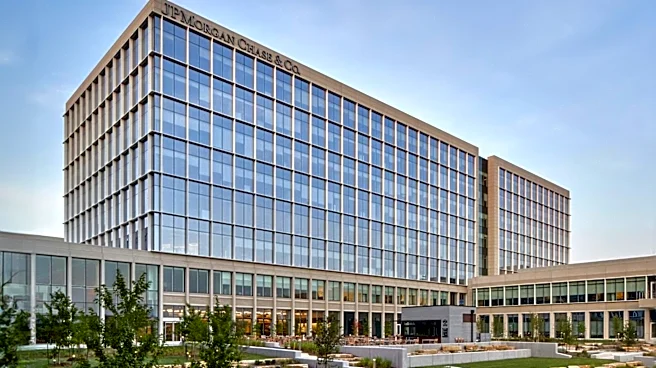
JPMorgan Chase stated that a software bug in its internal systems caused service slowdowns for some customers and potentially affected other banks when transactions involved Chase accounts. The bank clarified that customers still had access to their accounts and funds and that the issue was not systemic. Other financial services like PNC, US Bank, and the Zelle money transfer app also experienced issues, with Zelle and Capital One suggesting their problems were indirect consequences of the issues at partner banks like Chase. This incident follows recent technical disruptions affecting air travel and Microsoft services.
Why It's Important?
The widespread outages across multiple major U.S. banks highlight the interconnectedness and potential vulnerabilities within the nation's financial infrastructure. Even a localized software bug at one large institution, like JPMorgan Chase, can have ripple effects across the entire banking ecosystem, impacting numerous other banks and financial applications like Zelle. This event underscores the critical need for robust cybersecurity measures and resilient IT systems to prevent disruptions that can affect millions of consumers and businesses. Such outages can erode public trust in digital banking services and potentially lead to significant economic inconvenience, especially for individuals and businesses reliant on immediate access to funds and online transactions. The incident also raises questions about the systemic risks posed by highly integrated financial technologies.
What's Next?
JPMorgan Chase indicated it was working to resolve the software bug by the end of the day. Following this incident, there will likely be increased scrutiny on the IT infrastructure and contingency plans of major financial institutions. Regulators may push for enhanced stress testing of banking systems to ensure resilience against similar technical failures. Banks, in turn, may accelerate investments in system upgrades, redundancy measures, and cybersecurity protocols to prevent future widespread disruptions. Consumers might also become more cautious about relying solely on digital banking, potentially leading to a temporary increase in branch visits or a diversification of banking methods.
Beyond the Headlines
The recent series of technical disruptions, including those affecting major banks, air travel, and Microsoft services, points to a broader societal vulnerability to technological failures. This trend raises concerns about the increasing reliance on complex digital systems across critical sectors and the potential for cascading failures. Beyond the immediate inconvenience, such incidents can fuel public anxiety about the stability of essential services and the security of personal data. The interconnectedness of these systems means that a single point of failure can have far-reaching consequences, prompting a deeper conversation about digital resilience, infrastructure investment, and the balance between technological advancement and operational stability in a highly digitized world.