
What's Happening?
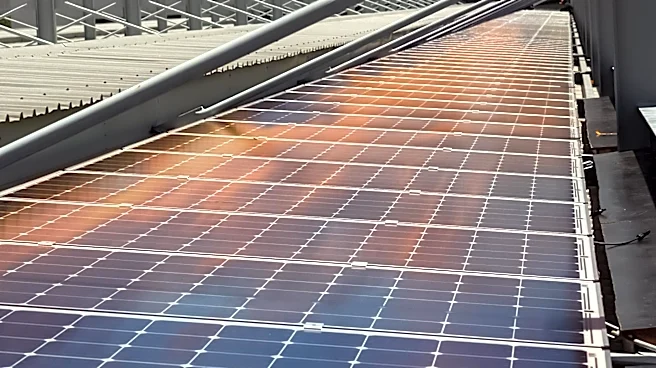
Cumulative solar photovoltaic (PV) manufacturing capital expenditure (capex) in the United States is projected to hit $12.2 billion by the end of 2026, according to a new report from Terawatt PV Research. This figure represents over 50% of all U.S. solar PV manufacturing spending
since 2001 and is largely stimulated by the Inflation Reduction Act (IRA) introduced in 2022. Since the IRA's implementation, U.S. solar PV manufacturing capex has exceeded $2.5 billion annually, with a record $4.14 billion spent in 2024. Major contributors to this surge include First Solar, with investments in Alabama and Louisiana, and Qcells (part of Hanwha Solutions), with its vertically-integrated investments in Georgia. The report highlights that factory build-out spending, encompassing buildings and infrastructure, accounts for approximately 60% of the total capex during the 2023-2026 period.
Why It's Important?
This significant increase in U.S. solar manufacturing capex signals a robust revitalization of the domestic solar industry, directly attributable to the Inflation Reduction Act. It underscores a strategic shift towards strengthening the U.S. supply chain for renewable energy, reducing reliance on foreign manufacturing, and fostering economic growth within the country. The substantial investment in new factories and infrastructure creates jobs, stimulates local economies, and enhances national energy security. Furthermore, the focus on greenfield cell spending reaching global highs indicates a commitment to advanced manufacturing capabilities. This trend is crucial for meeting ambitious climate goals and positioning the U.S. as a leader in clean energy technology, while also mitigating risks associated with global supply chain disruptions and geopolitical tensions.
What's Next?
The report forecasts continued growth in U.S. solar PV manufacturing out to 2030, with ongoing investments arising from Section 232 of the IRA. The analysis will continue to track key quarterly metrics at individual PV manufacturing sites, including effective ramped capacity, production output, technology segmentation, and manufacturing capex. The emergence of regional clusters, particularly in Texas as a major hub for c-Si module assembly, and the Southeast (Louisiana, Florida, Carolinas, Georgia, Alabama) for advanced manufacturing, suggests strategic development of material supplies and localized production ecosystems. The industry will also focus on improving effective capacity conversion rates, which currently vary significantly, to maximize production volumes. The first Manufacturing Strength Ratings Pyramid for U.S. solar PV manufacturers will be revealed at the Solar Manufacturing USA 2026 conference, providing a comprehensive ranking and rating of companies based on their production and capex.
Beyond the Headlines
The IRA's impact on U.S. solar manufacturing extends beyond economic metrics, fostering a renewed sense of industrial self-reliance and technological leadership. The emphasis on domestic production addresses concerns about national security and economic resilience, particularly in critical sectors like energy. This investment also highlights the broader implications of government policy in shaping industrial landscapes and driving innovation. The detailed segmentation of capex across buildings, equipment, and maintenance provides insights into the foundational elements required for a sustainable manufacturing base. The long-term success of these initiatives will depend on sustained policy support, technological advancements, and the ability to attract and retain a skilled workforce. The regional clustering of manufacturing facilities could also lead to specialized expertise and localized economic benefits, creating new hubs of innovation and employment.