



What's Happening?
The U.S. 11th Circuit Court of Appeals has ruled that Zurich American Insurance Company cannot reclassify a $12 million claim for rain damage to a Georgia solar farm as a flood event, which would have significantly increased the deductible. The court
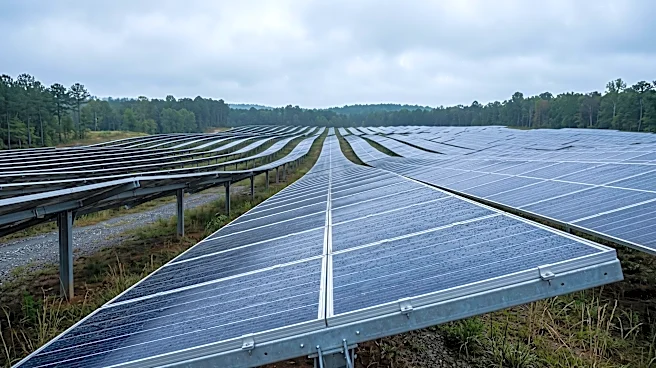
upheld a lower court's decision, stating that Zurich American waived its right to apply a higher flood deductible after initially classifying the damage as water damage and making advance payments. The case involves a 200-megawatt solar plant near Warner Robins, Georgia, constructed by First Solar, which sustained extensive damage from five heavy rain events in 2019 and 2020. Initially, a Zurich adjuster determined the loss was due to water damage, with a $100,000 per-event deductible, and Zurich paid $600,000 for the first three events. However, Zurich later reversed its stance, arguing the events were floods, which carried a $2.5 million per-event deductible, effectively negating any payout. The district court had previously ruled in favor of First Solar, awarding $12.2 million.
Why It's Important?
This ruling is significant for the insurance industry and policyholders, particularly those in large-scale infrastructure projects like solar farms. It reinforces the principle that insurers may waive their rights to reclassify claims or apply different deductibles if they do not explicitly reserve those rights or if their initial actions lead the policyholder to believe a certain coverage applies. This decision emphasizes the importance of clear communication and consistent claim handling by insurance companies. For businesses, it provides a degree of certainty that initial claim assessments and payments by insurers carry weight and cannot be easily reversed to their detriment. The case also highlights the complexities in defining 'water damage' versus 'flood damage' in insurance policies, a distinction that can have multi-million dollar implications for coverage and deductibles, especially in regions prone to heavy rainfall.
What's Next?
The 11th Circuit Court of Appeals upheld the district court's decision regarding the first three rain event claims, affirming that Zurich American waived its right to apply the higher flood deductible for those incidents. However, the appellate court remanded the case for further deliberations on the two later rainfall events. This means that while the core principle of waiver has been established for the initial claims, the specifics of the remaining claims will require additional legal proceedings at the district court level. The outcome of these further deliberations will determine the final financial liability for Zurich American concerning the latter two events. This case may also prompt insurance companies to review and clarify their policy language regarding water versus flood damage and to implement stricter protocols for reserving rights when making initial claim assessments or advance payments to avoid similar waiver disputes in the future.
Beyond the Headlines
This case delves into the broader implications of contract interpretation and the doctrine of waiver in insurance law. The court's analogy to a 'mulligan' in golf vividly illustrates its stance against insurers getting a 'do-over' after an initial assessment. This ruling could influence how insurance adjusters are trained and how claims are processed, pushing for more definitive initial assessments and clear communication of any reservations of rights. Ethically, it underscores the importance of good faith and fair dealing in insurance contracts, preventing insurers from retroactively altering terms to avoid payouts after a policyholder has relied on an initial determination. Legally, it contributes to the body of case law defining the boundaries of an insurer's ability to change its coverage position, particularly when such changes would significantly impact the policyholder's financial recovery. The decision also highlights the ongoing challenges in drafting precise insurance policy language that accounts for all potential scenarios of water-related damage.