
What's Happening?
The FAO Food Price Index saw a 1.2% decrease in October 2026, reaching 133.9 index points, a moderation from its 2022-highs recorded in September. This decline was primarily driven by a 4.5% drop in cereal
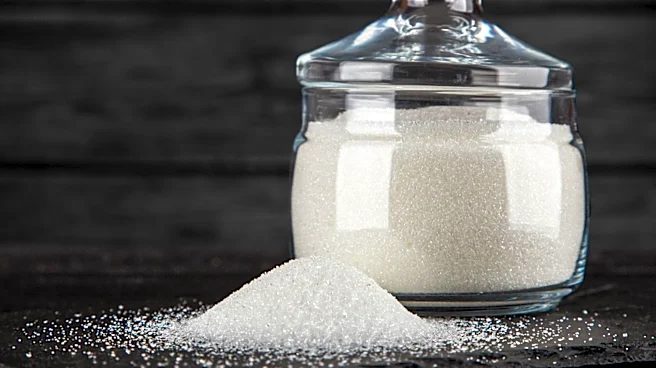
prices, influenced by subdued international demand and an improved production outlook, particularly in Argentina. Meat costs also fell by 1.2%, with reductions in pig, ovine, and bovine meat quotations, while poultry prices remained stable. Dairy prices decreased by 1.1%, attributed to lower international butter and cheese quotations, despite an increase in milk powder prices. However, this overall moderation was partially offset by increases in other categories. Vegetable oil prices edged up 0.3%, reaching a new high since June 2022, mainly due to higher soybean and sunflower oil quotations. Sugar prices experienced a significant jump of 6.6%, hitting a fresh 2024-high, primarily due to rainfall-related disruptions to sugarcane harvesting and crushing operations in Brazil's key Centre-South producing region.
Why It's Important?
The mixed trends in global food prices reflect a complex and dynamic market environment. While the overall moderation from 2022-highs offers some relief, the increases in specific commodities like sugar and vegetable oils indicate persistent inflationary pressures in certain sectors. The decline in cereal and meat prices could benefit consumers and food importers, potentially easing some cost-of-living pressures. Conversely, the sharp rise in sugar prices, driven by weather-related supply disruptions in a major producing region like Brazil, highlights the vulnerability of global food markets to localized climatic events. This volatility can impact food manufacturers and consumers, particularly in countries heavily reliant on imported sugar and vegetable oils, potentially leading to higher prices for processed foods and beverages. The varied movements across different food categories underscore the need for diverse supply chain strategies and risk management in the food industry.
What's Next?
The future trajectory of global food prices will depend on several factors, including weather patterns in key agricultural regions, international demand, and geopolitical stability. The ongoing disruptions in Brazil's sugarcane harvesting could sustain high sugar prices in the short to medium term. Similarly, the slight increase in vegetable oil prices suggests continued demand and potential supply constraints. While cereal and meat prices have shown a downward trend, any unforeseen events, such as adverse weather or trade policy changes, could quickly reverse this. Stakeholders in the food industry will need to closely monitor these commodity markets to anticipate and adapt to potential price fluctuations, which could influence sourcing decisions, production costs, and ultimately, consumer prices. The overall trend suggests a continued period of market adjustments rather than a uniform decline in food costs.
Beyond the Headlines
The nuanced movements within the FAO Food Price Index reveal the intricate web of factors influencing global food security. The divergence between falling cereal and meat prices and rising sugar and vegetable oil prices illustrates how different agricultural sectors are affected by distinct supply and demand dynamics. This complexity challenges simplistic narratives about overall food inflation and highlights the importance of disaggregated data for accurate analysis. The impact of climate change, as evidenced by rainfall disruptions in Brazil affecting sugar production, is becoming an increasingly prominent factor in commodity markets. This situation underscores the need for resilient agricultural practices and diversified supply sources to mitigate the effects of climate-related shocks. Furthermore, the stability of global food prices has significant implications for political stability and social welfare, particularly in import-dependent nations.