
What's Happening?
MP Materials recently announced its third-quarter results, revealing a beat on revenue and production updates, alongside narrowed losses and new contract advancements. Despite these positive developments, including contract wins with General Motors, Apple,
and U.S. defense customers, the company's share price has experienced a downturn. Over the past month, shares have fallen by 21%, and year-to-date, they are down 34%. This contrasts with a stronger earlier performance, reflected in a three-year total shareholder return of approximately 126%. The company's valuation is currently a subject of debate, with some analysts suggesting it is 49% undervalued based on future cash flows and long-term earnings potential, while others argue it appears expensive when viewed through a simple price-to-sales lens.
Why It's Important?
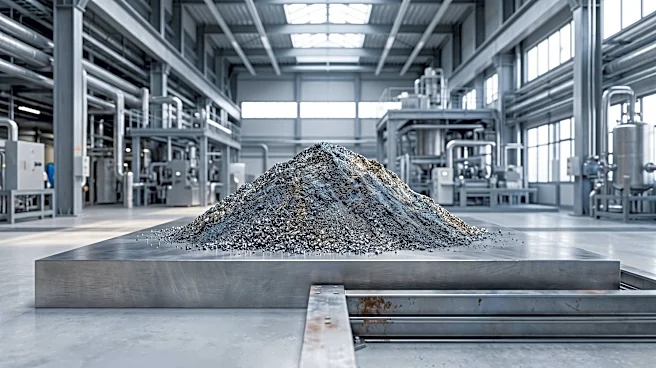
The performance of MP Materials is significant for the U.S. industrial sector, particularly in the context of rare earth materials and domestic manufacturing capabilities. As the company aims to scale high-margin magnet and heavy rare earth production, its success directly impacts the supply chain for critical components used in various industries, including automotive (General Motors), consumer electronics (Apple), and defense. The debate over its valuation highlights the inherent risks and opportunities in capital-intensive expansions and the reliance on large customer contracts. A successful ramp-up could bolster U.S. self-sufficiency in rare earth processing and magnet manufacturing, reducing dependence on foreign sources. Conversely, delays or failures in scaling production could lead to increased costs and continued reliance on international suppliers, affecting national security and economic competitiveness.
What's Next?
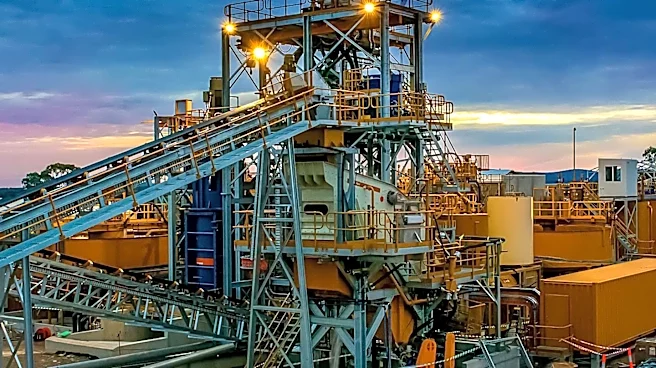
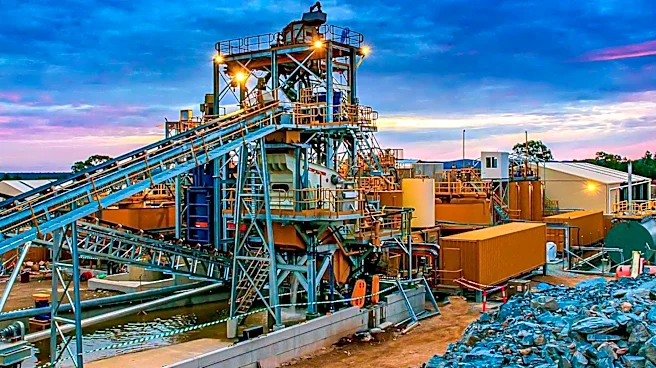
MP Materials' future trajectory hinges on the successful and timely completion of its capital-intensive expansion projects, particularly the ramp-up of high-margin magnet and heavy rare earth production across its Independence, 10X, and Mountain Pass facilities. The company also needs to effectively manage start-up costs and navigate its concentrated customer and government exposure. The bullish outlook for MP Materials is predicated on its ability to meet projected NdPr production ramps and achieve magnet EBITDA margins above 40%, supported by long-term offtake structures. Investors will be closely watching for updates on these operational milestones and the company's ability to convert its contracted cash flow potential into sustained earnings, which could either validate the 'undervalued' narrative or reinforce concerns about its current sales-based valuation.
Beyond the Headlines
The situation with MP Materials extends beyond immediate financial metrics, touching upon broader strategic implications for the U.S. economy and national security. The company's efforts to establish a fully vertically integrated rare earth supply chain outside of China are crucial for reducing geopolitical vulnerabilities and ensuring access to essential materials for advanced technologies and defense applications. The challenges MP Materials faces, such as managing capital-intensive expansions and securing large customer commitments, underscore the complexities of re-shoring critical manufacturing capabilities. The ongoing debate about its valuation also reflects a tension between long-term strategic importance and short-term financial performance, highlighting how investors weigh future potential against current market realities in a sector vital for technological independence.