

What's Happening?
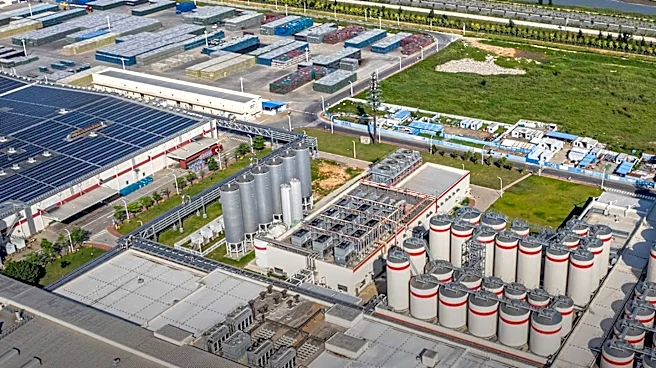
Defiance ETFs has introduced the Defiance Global Foundries ETF (ticker: AIFR), the first U.S.-listed Exchange Traded Fund (ETF) specifically dedicated to semiconductor foundries. This new ETF aims to capitalize on the increasing importance of chip manufacturers,
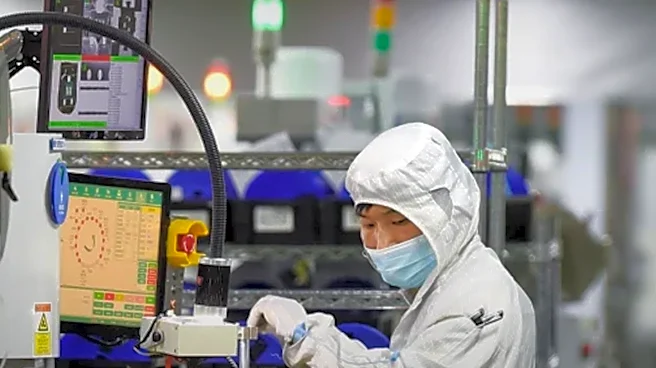
particularly in the artificial intelligence (AI) sector. The fund tracks the MarketVector Global Foundries index, which includes 10 companies that generate at least half of their revenue, or a minimum of $2 billion annually, from foundry activities. The launch comes as the AI industry experiences a proliferation of accelerators, networking chips, custom ASICs, and power-management components, making the factories that produce these advanced semiconductors a critical choke point. Taiwan Semiconductor Manufacturing Company (TSMC) currently dominates the pure-play foundry market, holding 73% of the global share in the second quarter. High utilization rates across the industry are enabling manufacturers to increase both prices and volumes, with TSMC reportedly raising prices by 5 to 10 percent on certain nodes and Samsung Foundry implementing similar increases.
Why It's Important?
The launch of the Defiance Global Foundries ETF highlights a significant shift in investment focus within the semiconductor industry. While previous investment trends centered on chip designers like Nvidia and AMD, the new ETF underscores the growing recognition of the manufacturing segment as a key driver of value and a potential bottleneck. The concentration of advanced semiconductor manufacturing in a few capital-intensive foundries, particularly TSMC, creates a scenario of pricing power for these manufacturers. This is crucial for the U.S. economy and its technological leadership, as the reliance on a limited number of overseas foundries for critical components poses supply chain risks. The increasing demand for AI chips further amplifies this importance, as the availability and cost of these foundational components directly impact the development and deployment of AI technologies across various U.S. industries. The ability of foundries to raise prices and maintain high utilization rates indicates a robust demand environment, but also signals potential cost pressures for companies reliant on these chips.
What's Next?
The semiconductor foundry market is expected to continue experiencing high demand, driven by the expanding AI sector and other advanced technologies. Foundries will likely continue to invest heavily in research and development and expand their manufacturing capacities to meet this demand. TSMC, for instance, has increased its 2026 capital expenditure guidance to $60 billion-$64 billion, with a significant portion directed towards 2nm capacity and advanced packaging. This substantial investment, including a commitment of $265 billion in the U.S. for potential Arizona sites, indicates a long-term strategy to address the growing need for advanced chips. However, the capital-intensive nature of the foundry business means that while temporary shortages can lead to exceptional margins, these margins also attract significant capital investment, potentially altering the competitive landscape in the long run. Investors will be closely watching how these investments translate into increased capacity and whether new players or existing competitors like Samsung and China's SMIC can gain significant market share.
Beyond the Headlines
The emergence of an ETF focused on semiconductor foundries reflects a deeper understanding of the intricate and interdependent nature of the global technology supply chain. Beyond the immediate financial implications, this trend highlights the strategic importance of manufacturing capabilities in an era dominated by advanced computing. The concentration of foundry power in a few entities, particularly TSMC, raises geopolitical considerations and national security concerns for countries like the U.S., which are heavily reliant on these chips for defense, infrastructure, and economic competitiveness. The ongoing investments in expanding foundry capacity, both domestically and internationally, are not merely business decisions but strategic moves to secure critical technological infrastructure. This also underscores the need for robust talent pipelines and continuous innovation in manufacturing processes to maintain a competitive edge and mitigate future supply chain vulnerabilities.