
What's Happening?
Cisco Systems announced record-breaking financial results for the first quarter of fiscal year 2027, with revenue reaching $18.5 billion, marking a 24% increase year-over-year. Non-GAAP net income also saw a significant jump of 39% to $5.6 billion, translating
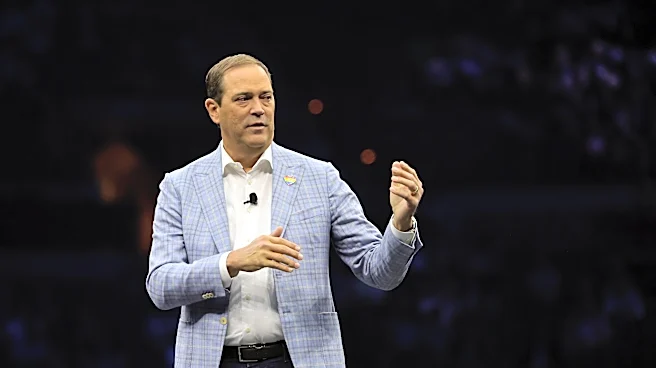
to $1.40 per share. Both revenue and adjusted earnings surpassed consensus analyst estimates. The company attributed a primary driver of this revenue growth to the increasing demand for artificial intelligence (AI) compute capacity and networking infrastructure. CEO Chuck Robbins stated that Cisco is in the early stages of a multi-year networking supercycle, confident in capturing the multi-billion-dollar opportunity it presents. Following these strong results, Cisco raised its full-year fiscal 2027 revenue guidance to a range of $74.8 billion to $75.8 billion, up from its previous forecast of $72.2 billion to $73.4 billion. The adjusted EPS estimate was also upgraded to $5.47 to $5.53, from $5.05 to $5.11.
Why It's Important?
This performance by Cisco Systems is significant as it highlights the robust demand for networking infrastructure, particularly driven by the rapid expansion of AI technologies. The company's record revenue and increased forecasts indicate a strong market position in a critical sector of the technology industry. The emphasis on AI compute capacity as a key growth driver underscores the ongoing investment by businesses and hyperscalers in advanced technological infrastructure. This trend suggests a broader economic shift towards AI integration across various industries, potentially leading to increased spending on high-performance networking solutions. For investors, Cisco's ability to exceed expectations and raise guidance, despite some market concerns, could signal underlying strength in the enterprise IT spending landscape, even as some analysts debate whether growth has peaked. The company's role in enabling the 'agentic AI era' positions it as a crucial player in the evolving digital economy.
What's Next?
Despite the positive earnings report and raised guidance, Cisco's stock experienced a decline, driven by investor concerns over a slowdown in product order growth and narrowing profit margins. Total product orders, while solid, showed a decelerating growth rate compared to the previous quarter. Additionally, the adjusted gross margin decreased to 65.6% from 68.1% a year ago, primarily due to higher costs for memory components and a greater contribution from lower-margin AI networking products. CFO Mark Patterson indicated anticipated 'tougher compares and a little bit less visibility' in the second half of the fiscal year. Investors will closely monitor Cisco's ability to manage these margin pressures and maintain revenue growth, especially as demand for AI infrastructure continues to evolve. The company's full-year gross margin outlook and its $9 billion AI infrastructure revenue target will serve as key benchmarks for evaluating its performance in the coming quarters.
Beyond the Headlines
The mixed market reaction to Cisco's strong earnings report reveals a deeper investor scrutiny beyond headline figures, focusing on underlying trends like product order growth and profit margins. The decline in gross margin, attributed to higher component costs and a shift towards lower-margin AI networking products, highlights a potential challenge for hardware providers in the AI era. While AI drives significant revenue, it may also introduce complexities in maintaining profitability. This situation could prompt a re-evaluation of business models within the tech hardware sector, emphasizing efficiency and strategic product mix management. Furthermore, the market's sensitivity to growth rates, even when positive, suggests a high expectation for sustained, aggressive expansion in the technology sector. This dynamic could influence how companies communicate future outlooks and manage investor expectations in a rapidly evolving technological landscape.