
What's Happening?
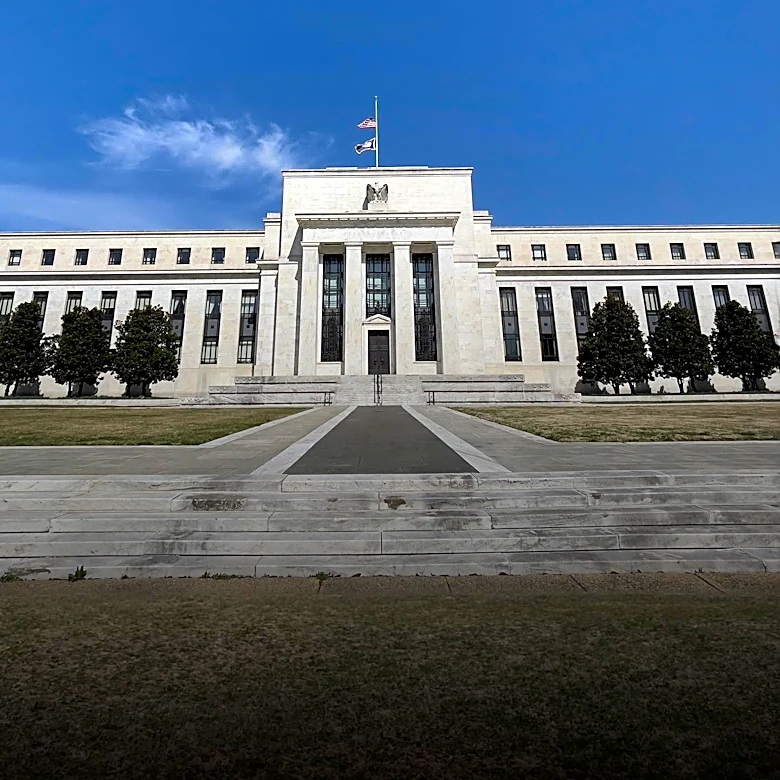
The American Bankers Association (ABA) has urged federal banking agencies to better coordinate their efforts in rewriting disclosure rules for confidential information. The call comes as the Federal Deposit Insurance Corporation (FDIC) and the Office
of the Comptroller of the Currency (OCC) have issued separate but related proposals aimed at balancing public disclosure with the protection of confidential supervisory information. These new rules generally propose allowing banks to share confidential information with certain parties without prior agency authorization, provided specific precautions are taken. They also seek to revise the agencies’ Freedom of Information Act (FOIA) processes. While the ABA acknowledged several improvements in the proposals, such as allowing supervised entities to make specified disclosures without prior approval, it raised concerns about the potential for differing standards across agencies. The ABA emphasized that many banking organizations are supervised by multiple federal and state agencies and manage information that may fall under various confidentiality rules, making standardized rules crucial to avoid operational burdens and uncertainty.
Why It's Important?
The lack of coordinated disclosure rules among federal banking agencies poses significant challenges for U.S. financial institutions, particularly those operating across multiple jurisdictions or with diverse business lines. Inconsistent standards can lead to increased operational burden, compliance costs, and legal uncertainty for banks, as they navigate varying requirements for sharing confidential information. This can delay routine information sharing, even when all parties have a legitimate need for the data and appropriate safeguards are in place. For the broader financial system, such inefficiencies can hinder effective risk management, inter-agency cooperation, and the timely flow of critical financial intelligence. A harmonized approach, as advocated by the ABA, would enhance transparency and predictability for banks, allowing them to better manage their disclosure obligations while preserving fundamental confidentiality protections. This coordination is essential for maintaining a stable and efficient banking sector, reducing regulatory friction, and ensuring that financial institutions can operate effectively without being unduly burdened by disparate rules.
What's Next?
The ABA's recommendations will be considered by the FDIC and OCC as they finalize their respective disclosure rules. The association has specifically requested that the agencies expand and clarify the circumstances under which institutions can disclose confidential information without prior approval. It also seeks greater transparency and predictability in the rules while preserving confidentiality protections. The outcome of this advocacy could lead to revisions in the proposed rules, potentially resulting in more harmonized and streamlined disclosure requirements across federal banking agencies. This would likely involve ongoing dialogue and collaboration between the ABA, the FDIC, and the OCC, and potentially other federal regulators like the Federal Reserve, to develop a more unified approach. The goal is to create a regulatory environment that supports efficient information sharing while safeguarding sensitive data, ultimately benefiting both financial institutions and the broader public interest.
Beyond the Headlines
The debate over disclosure rules for confidential banking information extends beyond mere procedural adjustments; it touches upon the delicate balance between regulatory oversight, market transparency, and the proprietary interests of financial institutions. The call for coordination highlights a systemic challenge in multi-agency regulatory environments, where different bodies may have overlapping jurisdictions but distinct approaches. This issue can lead to 'regulatory fragmentation,' potentially undermining the effectiveness of supervision and increasing compliance costs without necessarily enhancing safety and soundness. Furthermore, the discussion around the Freedom of Information Act process in this context underscores the public's right to information versus the need to protect sensitive financial data, including trade secrets and customer privacy. The long-term implications could involve a more integrated regulatory framework across U.S. financial agencies, fostering greater efficiency and clarity, and potentially influencing how other regulated industries manage information disclosure in complex regulatory landscapes.