
What's Happening?
Oil prices have experienced a decline at the start of the week, driven by reports indicating a return to oversupply in the global oil market. Brent crude was trading at $95.24 per barrel, and West Texas
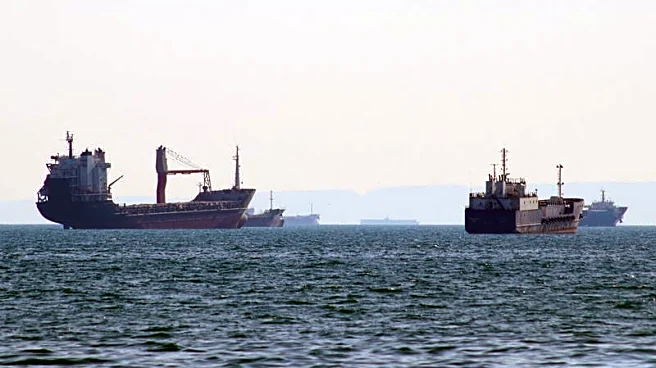
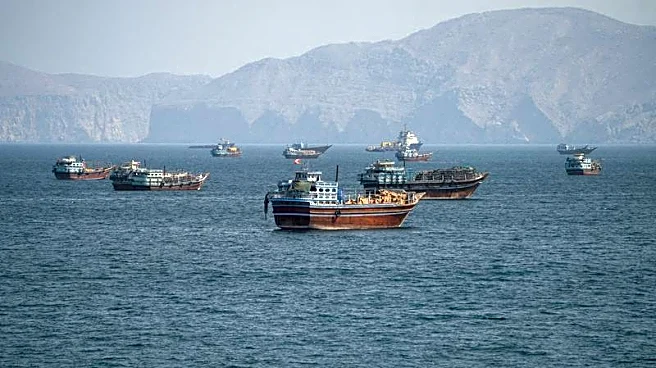
Intermediate (WTI) at $88.31 per barrel, both showing a slight decrease from Friday's closing figures. This dip follows a report from the International Energy Agency (IEA) suggesting that the oil market will shift into oversupply during the current quarter. The IEA attributes this to reduced demand, a consequence of previously higher prices, and a recovery in Middle Eastern supply. JP Morgan estimated a global oil market surplus of 1.1 million barrels per day in September, expanding to 1.4 million bpd in October. Goldman Sachs, while more cautious, also predicted a balanced market for September and October. This narrative of excess supply is dampening market sentiment, despite continued attacks on tankers in the Strait of Hormuz and Iraq's reliance on truck exports via Syria.
Why It's Important?
The reported return to global oil oversupply, despite ongoing geopolitical tensions, has significant implications for the U.S. economy and consumers. Lower oil prices can translate to reduced gasoline costs, providing relief to American households and potentially stimulating consumer spending. For U.S. industries, particularly those reliant on transportation and energy, decreased fuel costs can lower operational expenses, potentially boosting profitability. However, a sustained period of low oil prices could negatively impact U.S. domestic oil producers, potentially leading to reduced investment in exploration and production, and job losses in the energy sector. The shift in market sentiment from tightness to potential glut also highlights the complex interplay between supply-demand dynamics and geopolitical events, making future price movements difficult to predict. This situation could also influence U.S. energy policy decisions, particularly regarding strategic petroleum reserves and domestic production targets.
What's Next?
The oil market will likely continue to react to incoming data on supply and demand, as well as any new geopolitical developments. Traders and analysts will closely monitor reports from organizations like the IEA, JP Morgan, and Goldman Sachs for further indications of market balance or imbalance. The ongoing attacks in the Strait of Hormuz and the situation in Iraq remain critical factors that could disrupt supply and potentially reverse the current trend of falling prices. Conversely, if demand continues to be suppressed by economic factors or if Middle Eastern supply recovers more robustly, the oversupply could persist, leading to further price declines. U.S. policymakers will be observing these trends to assess their impact on inflation, economic growth, and energy security.
Beyond the Headlines
The current market dynamics reveal a deeper tension between short-term supply-demand fluctuations and long-term geopolitical risks. While the immediate focus is on oversupply, the underlying vulnerabilities in global energy supply chains, particularly in critical chokepoints like the Strait of Hormuz, remain. This situation underscores the fragility of the global energy system and the potential for rapid shifts in market conditions. The IEA's observation that annual global oil supply would be significantly lower than in 2025, despite the current oversupply, suggests a potential future tightening of the market. This could lead to a cycle of boom and bust, impacting investment decisions in both fossil fuels and renewable energy. The U.S. and other major economies face the challenge of navigating these short-term market signals while also planning for long-term energy security and transition away from fossil fuels.