
What's Happening?
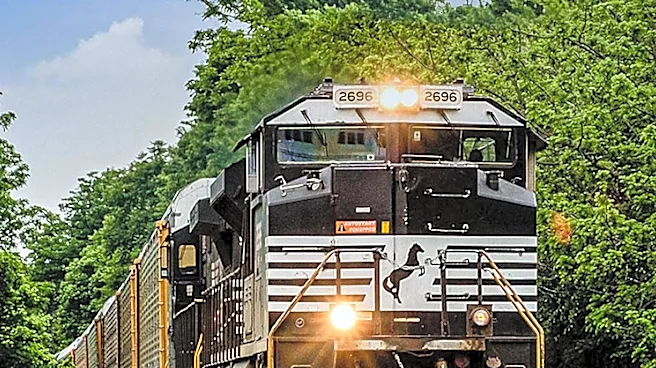
Norfolk Southern (NSC) stock has seen a significant 65.0% return over the past three years, leading to questions about whether its current share price of US$327.88 is justified by its projected cash flows.
According to Simply Wall St, a Discounted Cash Flow (DCF) analysis suggests that Norfolk Southern's estimated intrinsic value is substantially below its current share price. The analysis models the company based on its last twelve months' free cash flow of approximately $838.3 million, with analysts projecting higher annual cash flows over the next decade, settling into low single-digit growth. Additionally, the Surface Transportation Board's scrutiny of Union Pacific's comments regarding potential rate hikes introduces an extra layer of regulatory risk, which may contribute to the shares appearing expensive through a cash flow model, even as merger discussions keep the company in the news.
Why It's Important?
The discrepancy between Norfolk Southern's strong stock performance and its intrinsic value, as calculated by DCF, highlights a critical challenge for investors in the U.S. transportation sector. Overvaluation, if present, could expose investors to significant risk if future cash flows do not meet optimistic projections. The ongoing merger debate and regulatory oversight from the Surface Transportation Board are crucial factors influencing investor expectations for Norfolk Southern's future pricing power and free cash flow generation. This situation underscores the impact of regulatory environments and market narratives on stock valuations, particularly in industries with high capital expenditure and significant public interest like railroads. Investors need to carefully consider both historical performance and future regulatory and operational landscapes when assessing the true value of such companies.
What's Next?
Investors will be closely watching Norfolk Southern's future cash flow performance and any developments in the merger debate and regulatory landscape. The company's implementation of its PSR 2.0 transformation, aimed at unlocking network value, streamlining operations, and improving its operating ratio, is a key factor that could influence its future financial health and, consequently, its stock valuation. The outcome of the Surface Transportation Board's scrutiny of Union Pacific's potential rate hikes could also set precedents for pricing power across the railroad industry, directly affecting Norfolk Southern. Simply Wall St suggests that a deeper look into specific concerns and a focused stock screen built on valuation and quality filters could help investors assess whether the current share price is justified.
Beyond the Headlines
The situation with Norfolk Southern reflects a broader market dynamic where strong past performance can sometimes lead to an 'optimism premium' in stock prices that may not be fully supported by fundamental valuations. This can create a disconnect between market sentiment and intrinsic value, particularly in sectors undergoing significant change or regulatory review. The role of regulatory bodies like the Surface Transportation Board in influencing pricing power and market competition is a critical, often overlooked, aspect of valuation in regulated industries. This scenario also highlights the importance of robust financial modeling, such as DCF analysis, as a counterpoint to market narratives and short-term stock movements, providing a more grounded perspective on long-term investment potential.