

What's Happening?
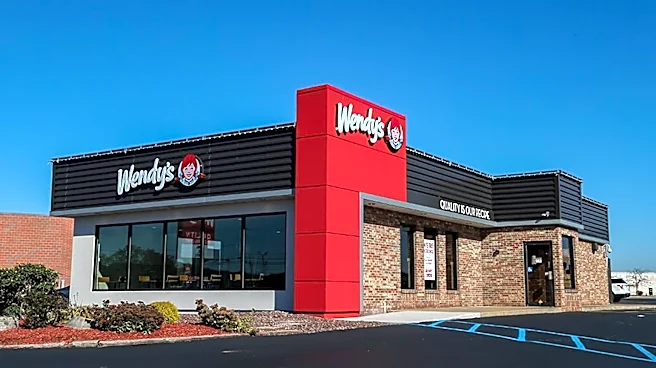
An investment group led by Trian Fund Management LP has submitted a non-binding proposal to acquire all outstanding shares of The Wendy's Co. for $7.35 per share in cash, totaling approximately $1.4 billion. This offer represents a 20% premium over Wendy's closing
share price of $6.14 on October 27. The group, which also includes BlueFive Capital, Sixth Street Partners, and Flynn Group (a major Wendy's franchisee), argues that Wendy's is at a 'critical juncture' due to challenging external factors such as consumer pressures, economic uncertainty, commodity inflation, and intense competition in the quick-service restaurant (QSR) burger category. They believe private ownership would provide the 'patient, long-duration capital' needed to revitalize the business.
Why It's Important?
This acquisition proposal highlights the increasing trend of private equity interest in established public companies, particularly those facing market headwinds. For Wendy's, a successful acquisition could lead to significant strategic shifts, potentially impacting its operations, menu, and competitive strategy within the highly competitive U.S. fast-food market. The offer's premium signals the investors' confidence in Wendy's underlying value, despite the current challenges. For the broader U.S. restaurant industry, such a move could set a precedent for how companies navigate economic pressures and intense competition. It also underscores the belief that private ownership can offer greater flexibility and a longer-term perspective for capital-intensive businesses, free from the short-term pressures of public markets. This could lead to more aggressive restructuring or investment in areas like technology and supply chain optimization.
What's Next?
Wendy's board of directors has formed an independent committee to evaluate the proposal, consulting with financial and legal advisers. The company has stated there is no assurance that the transaction will be pursued or that any definitive agreement will be approved. Shareholders are not required to take any action at this time. The independent committee's decision will be crucial, as it will weigh the benefits of the premium offer against the potential long-term value of remaining a public entity. The outcome could influence Wendy's strategic direction, its relationship with franchisees, and its ability to compete effectively in the evolving QSR landscape. Further announcements are expected only if deemed appropriate or necessary.
Beyond the Headlines
The investment group's rationale for private ownership—to provide 'patient, long-duration capital'—points to a fundamental tension between public market demands for short-term results and the long-term investment cycles often required for significant business transformation. This situation could spark a broader debate about the optimal ownership structures for mature companies in dynamic industries. The involvement of a major franchisee, Flynn Group, in the bidding consortium suggests a deep understanding of Wendy's operational challenges and potential for improvement, possibly indicating a more hands-on approach to management post-acquisition. This could lead to a more integrated and efficient franchise system, but also raises questions about potential conflicts of interest and the impact on other franchisees.