


What's Happening?
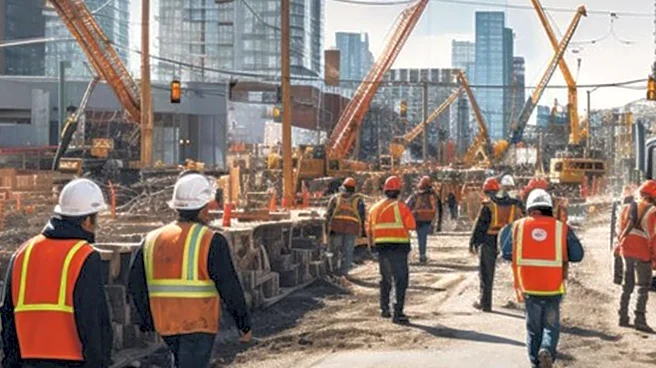
Builders risk insurance is a specialized property coverage designed to protect structures, materials, and equipment during construction projects or major renovations in the U.S. This type of insurance acts as a temporary property policy, safeguarding
against physical damage caused by events such as fire, wind, theft, and vandalism from the start of construction until the project's completion. It covers the structure itself at every stage, materials and supplies stored on-site or in transit, and temporary installations like scaffolding. However, it explicitly excludes worker injuries, third-party injuries, damage to neighboring properties, wear and tear, employee theft, and natural disasters like earthquakes and floods, which require separate coverage. The cost of builders risk insurance typically ranges from 1% to 5% of the total construction budget, with premiums influenced by factors such as construction value, materials used (e.g., wood-frame construction carries higher fire risk than steel or concrete), project location, timeline, and coverage limits. Property owners, general contractors, developers, builders, subcontractors, and lenders all have a financial interest in securing this coverage.
Why It's Important?
The importance of builders risk insurance in the U.S. construction industry cannot be overstated, as construction projects represent significant financial investments vulnerable to numerous risks. Without this specialized coverage, a fire, storm, or theft could lead to substantial financial losses and project delays that standard property policies would not cover. This directly impacts property owners, who could lose their investment, and contractors, who might face severe financial setbacks and contractual breaches. Lenders often mandate builders risk insurance as a condition for construction loans, highlighting its critical role in protecting their financial interests. The absence of such insurance could deter investment in new construction and major renovations, slowing down development and economic growth. Furthermore, the specific exclusions of builders risk insurance, such as worker injuries and third-party liability, underscore the necessity for comprehensive insurance planning within the construction sector, ensuring that all potential risks are adequately addressed through a combination of policies.
What's Next?
For those involved in U.S. construction projects, the immediate next step is to secure builders risk coverage before any work commences, as many carriers require the policy to be in place prior to the project start date and may not backdate coverage. Project stakeholders, including property owners and general contractors, should gather detailed information about their project, such as the total construction budget, timeline, type of structure, construction methods, materials, and job site location, to facilitate an accurate quote. Working with independent insurance agents is recommended, as builders risk insurance is a specialized product not universally offered by all companies, and online quotes are often unavailable. If a project experiences delays, policyholders must contact their agent promptly to discuss extensions, as allowing a policy to lapse mid-project leaves the investment unprotected and can complicate matters with lenders. Additionally, stakeholders should review their policies carefully to identify any gaps, particularly regarding tools and equipment, which may require separate inland marine or contractor’s equipment policies for broader protection.
Beyond the Headlines
Beyond its immediate financial protection, builders risk insurance reflects a broader understanding of risk management within the U.S. construction sector. The detailed exclusions within these policies, such as those for poor workmanship or faulty design, emphasize the industry's reliance on quality control and professional standards. This implicitly encourages best practices in construction, as insurers are less likely to cover losses stemming from preventable issues. The requirement for separate coverage for worker injuries (workers' compensation) and third-party liability (general liability) highlights the complex legal and ethical responsibilities associated with construction sites, pushing companies to maintain robust safety protocols and comprehensive legal protections. This layered approach to insurance coverage underscores a societal expectation that construction projects not only be financially sound but also safe and responsibly managed, impacting everything from labor practices to urban development and public safety standards.