
What's Happening?
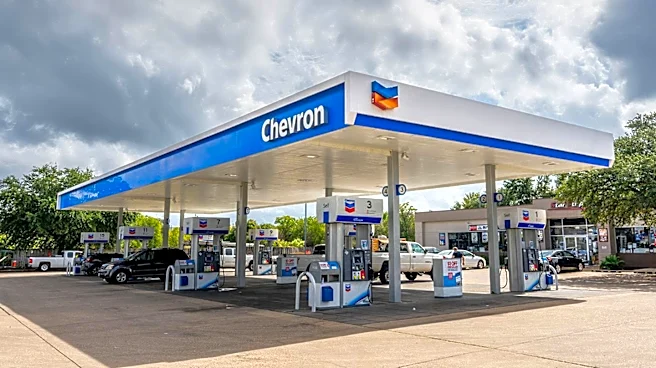
Chevron's stock experienced a decline of approximately 2.6%, settling at $212.115 on Wednesday. This dip occurred as the company announced it has secured roughly one-fifth of its targeted Liquefied Natural
Gas (LNG) supply portfolio through third-party contracts. Chevron aims for an annual LNG supply capacity of around 20 million metric tons. Of this target, about 16 million tons are expected to come from company-linked projects, with the remaining four million tons sourced from U.S. Gulf Coast producers. The company is actively exploring additional growth opportunities in various international regions, including Argentina, the eastern Mediterranean, Australia, and Africa. India is also identified as a significant potential demand market, though no supply agreements have been finalized there yet. This strategy allows Chevron to expand its LNG footprint more rapidly without solely relying on its own production capabilities.
Why It's Important?
This development is significant for Chevron as it highlights a strategic shift towards diversifying its LNG supply sources through external contracts, rather than solely through proprietary production. This approach enables faster market penetration and expansion of its LNG operations, which is crucial in meeting growing global energy demands. The reliance on U.S. Gulf Coast producers for a substantial portion of its contracted supply underscores the increasing importance of American energy exports in the global market. However, the stock's decline suggests investor caution, possibly due to the company's valuation, which is currently trading 30.73% above its GF Value estimate. This premium valuation implies that investors will demand disciplined contract economics, dependable execution, and strong returns on capital to justify the current stock price, rather than simply an increase in headline capacity. The move also aligns with a broader industry push towards dependable, long-duration energy demand, exemplified by Chevron's 20-year agreement to supply power to a Microsoft data center in Texas.
What's Next?
Chevron is expected to continue its pursuit of additional growth opportunities in key regions such as Argentina, the eastern Mediterranean, Australia, and Africa, with India remaining a potential demand market. The company's strategy of leveraging third-party contracts for LNG supply is likely to persist as it seeks to achieve its 20 million metric tons annual target. Future developments will likely focus on the execution and profitability of these contracts, as well as the progress of its company-linked projects. Investors will be closely monitoring Chevron's ability to demonstrate disciplined contract economics and strong returns on capital, especially given its current valuation. Any further announcements regarding new supply agreements or expansions in target regions will be critical in shaping investor sentiment and the company's stock performance. The success of its 'contract-heavy' approach will determine if it can broaden its LNG footprint effectively and profitably.
Beyond the Headlines
The strategy of securing a significant portion of its LNG supply through third-party contracts reflects a broader trend in the energy sector towards more flexible and diversified supply chain management. This approach can mitigate some of the capital expenditure and operational risks associated with developing entirely new production facilities. By partnering with U.S. Gulf Coast producers, Chevron is not only expanding its portfolio but also potentially strengthening regional energy infrastructure and fostering economic activity in those areas. However, this also introduces new dependencies and potential risks related to the reliability and pricing of third-party suppliers. The market's reaction, as evidenced by the stock dip despite increased capacity, suggests that investors are increasingly scrutinizing the financial terms and long-term profitability of such arrangements, emphasizing the need for robust execution and clear value creation beyond mere volume growth. This highlights a shift in investor focus from sheer scale to sustainable and profitable growth models in the energy transition.