

What's Happening?
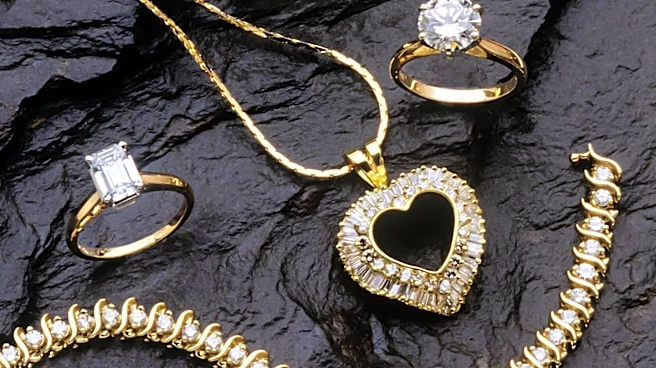
Schwarzschild provides a guide on jewelry insurance, explaining its purpose and how it functions for U.S. consumers. Jewelry insurance covers damage or theft of valuable pieces, offering peace of mind and financial protection. The guide outlines three
main types of coverage typically available through a homeowner's or renter's insurance policy: basic coverage, blanket coverage, and scheduled jewelry insurance. Basic coverage, while easiest to obtain, usually has a low cap on theft (around $1,500) and requires meeting a deductible. Blanket coverage raises this limit and expands what the policy covers. Scheduled jewelry insurance offers the broadest protection for specific, high-value items, with no cap, but requires a professional appraisal. It's important to note that insurance does not cover wear and tear, intentional damage, or pre-existing damage. For those concerned about claims affecting their existing policy premiums, standalone jewelry insurers offer policies covering loss, theft, mysterious disappearance, worldwide travel, and flood/earthquake damage.
Why It's Important?
For U.S. consumers, understanding jewelry insurance is crucial for protecting significant financial and sentimental investments. The guide highlights the importance of proper valuation through professional appraisals, which directly impacts the compensation received in case of a claim. The distinction between different coverage types—basic, blanket, and scheduled—allows consumers to choose the most appropriate level of protection based on the value and nature of their jewelry collection. The advice to keep appraisals current is particularly vital, as an item's appreciation in value might not be covered if the policy isn't updated. This information empowers consumers to make informed decisions, preventing potential financial losses and ensuring that cherished heirlooms or valuable purchases are adequately safeguarded against unforeseen events like theft or damage. The availability of standalone policies also offers flexibility for those who prefer not to link their jewelry coverage to their home insurance.
What's Next?
Consumers interested in insuring their jewelry should first obtain a professional appraisal to establish the item's value, as recommended by Schwarzschild. Following the appraisal, individuals can consult with their insurance agent or a dedicated jewelry insurer to determine the most suitable coverage type—whether it's an add-on to an existing homeowner's policy or a standalone policy. The process involves documenting all relevant information, including photos, receipts, and certificates, and understanding that premiums typically range from 1-2% of the item's value, based on appraisal, item type, and location. Regular review and updating of appraisals are essential to ensure continued adequate coverage, especially as market values for jewelry can fluctuate. In the event of a loss or theft, immediate reporting and providing thorough documentation will be critical for a successful claim.
Beyond the Headlines
The discussion around jewelry insurance touches upon broader themes of asset protection and the emotional value attached to personal possessions. Beyond the financial aspect, jewelry often carries significant sentimental weight, making its loss particularly distressing. The need for specialized insurance underscores the inadequacy of standard home insurance policies for high-value items, prompting consumers to consider tailored solutions. This also highlights the role of professional appraisers in the U.S. market, whose expertise is critical for accurate valuation and, consequently, fair insurance coverage. The emphasis on documentation and regular policy updates reflects a general principle in insurance: proactive management is key to effective protection. Furthermore, the option of standalone policies suggests a growing market for niche insurance products that cater to specific consumer needs, moving beyond one-size-fits-all solutions and offering more granular control over asset protection strategies.