

What's Happening?
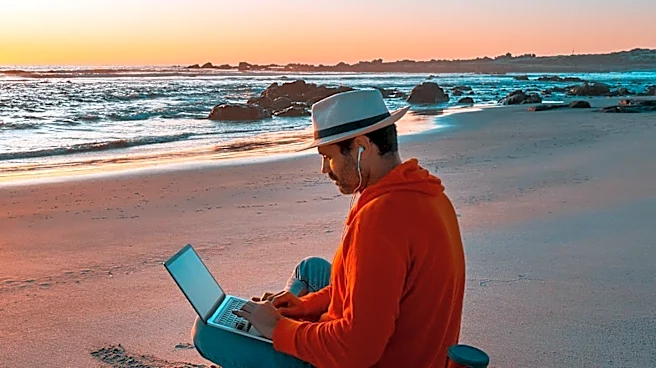
U.S. citizens working remotely abroad encounter significant complexities in managing their finances and complying with tax regulations. Traditional banking systems are often ill-suited for digital nomads who lack permanent addresses, receive income from
multiple international sources, and spend in various currencies. This leads to issues such as foreign transaction fees, ATM withdrawal charges, and potential account closures by U.S. banks if they discover a customer no longer resides in the country. Furthermore, U.S. tax reporting requirements, including the FBAR (FinCEN Form 114) and Form 8938, mandate that citizens report foreign financial accounts if their total value exceeds specific annual thresholds, regardless of whether the accounts generate taxable income. Failure to comply can result in substantial penalties. Many foreign banks also require proof of local residency, making it difficult for nomads to open accounts in new countries.
Why It's Important?
The financial and regulatory hurdles faced by U.S. digital nomads highlight a growing disconnect between traditional financial systems and the evolving nature of global work. This situation impacts thousands of Americans choosing location-independent careers, potentially limiting their financial flexibility and increasing their administrative burden. The stringent U.S. tax reporting requirements for foreign accounts are particularly significant, as they apply to all citizens regardless of their residency, making financial planning more complex for those living abroad. This can deter some from pursuing digital nomad lifestyles or lead to inadvertent non-compliance, resulting in severe financial repercussions. The need for specialized banking solutions, such as multi-currency accounts and fee-free international spending cards, underscores a market gap that traditional institutions are slow to address, affecting the economic well-being and operational efficiency of this demographic.
What's Next?
Digital nomads are increasingly adopting layered banking strategies, combining a U.S. anchor account with multi-currency operational accounts and specialized spending cards to navigate international finance. Financial technology companies are likely to continue innovating to provide more tailored solutions for this demographic, offering services that simplify international transactions and currency conversions. U.S. citizens working abroad will need to remain vigilant about understanding and fulfilling their tax reporting obligations, potentially seeking advice from tax professionals specializing in international taxation. As the digital nomad movement grows, there may be increased pressure on traditional banks and regulatory bodies to adapt their policies and services to better accommodate the needs of a globally mobile workforce, potentially leading to new financial products or clearer guidelines for international banking and tax compliance.
Beyond the Headlines
The challenges faced by U.S. digital nomads in banking and tax compliance reflect broader issues of national sovereignty in a globalized world. The U.S. approach to citizen-based taxation, which taxes income regardless of residency, is unique among developed nations and creates significant administrative burdens for expatriates. This policy raises ethical questions about fairness and the practicalities of enforcing tax laws across borders. The reliance on digital solutions for banking and payments also highlights the increasing importance of cybersecurity and data privacy for individuals operating across multiple jurisdictions. Ultimately, the complexities faced by digital nomads underscore the need for international cooperation in financial regulation and taxation, as well as the potential for technology to bridge gaps between traditional systems and modern work lifestyles, while also creating new challenges related to compliance and financial inclusion.