
What's Happening?
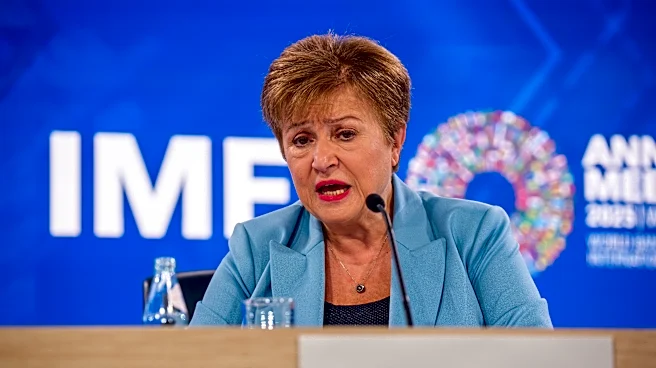
IMF Managing Director Kristalina Georgieva stated at the Asia-Pacific Economic Cooperation (APEC) summit in Shenzhen that global inflation is projected to reach 4.7% this year, driven by an energy-supply
shock and AI-driven demand. She emphasized the need for tighter monetary policies in many economies. According to Economic Daily News (UDN), Georgieva highlighted that expectations of AI-driven growth, coupled with significant government and corporate bond issuance, are pushing interest rates higher, with bond yields in many advanced economies at their highest in decades. She also noted that global debt is nearing 100% of GDP, a level not seen since World War II. The IMF's October World Economic Outlook attributes most of the 2026 inflation increase to energy and food prices, with petroleum projected to average $96 a barrel in 2026. The Outlook also models AI's price pressure through scenarios, indicating potential capacity constraints in chips, data centers, power, and skilled labor.
Why It's Important?
The IMF's assessment underscores significant economic pressures facing the U.S. and global economies. For American borrowers, the rising interest rates, partly fueled by AI-driven growth expectations and increased bond issuance, could translate into higher borrowing costs for mortgages, business loans, and consumer credit. The Federal Reserve's upcoming decisions on interest rates will be crucial, especially given the split within the Fed on the need for further hikes. If capacity constraints in AI-related sectors bind, U.S. inflation could rise by an additional 0.4 percentage points by 2028, potentially leading to higher policy rates. The increasing global debt, nearing 100% of GDP, also poses a long-term risk to financial stability, potentially impacting the U.S. economy through higher interest payments on its own substantial national debt. Energy prices, a primary driver of inflation, directly affect U.S. consumers and businesses through fuel and utility costs.
What's Next?
The Federal Reserve is scheduled to meet on December 8-9, with its decision announced on December 9, which will indicate whether the committee majority moves towards further interest rate hikes. The November consumer price report, due on December 10, will provide critical data influencing the Fed's stance. The IMF's next forecast update will reveal if the 4.7% inflation projection holds, and whether its guidance for monetary policy—tightening in tech-linked economies and caution in energy importers—remains relevant. Policymakers in the U.S. will need to consider these global economic trends and the IMF's recommendations when formulating domestic monetary and fiscal policies. The ongoing developments in AI adoption and energy markets will continue to be key factors shaping inflation and interest rate trajectories.
Beyond the Headlines
The IMF's focus on AI as a significant economic force highlights a deeper shift in global economic dynamics. While AI promises productivity gains, its rapid adoption is creating demand shocks that expose capacity constraints in critical sectors like chip manufacturing, data centers, and energy. This could lead to a new form of inflation driven by technological advancement, rather than traditional demand-pull or cost-push factors alone. The concentration of AI computing hardware trade in Taiwan and Korea, and AI hardware imports in China and the U.S., also points to potential geopolitical implications and supply chain vulnerabilities. Furthermore, the substantial increase in borrowing for advanced computing, representing a significant portion of nonfinancial investment-grade corporate debt, raises questions about potential financial stability risks if AI earnings do not meet expectations, particularly given large global holdings of U.S. equities.