


What's Happening?
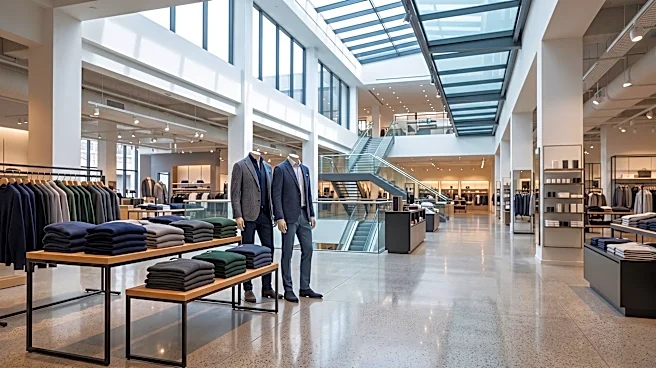
Dillard's (NYSE:DDS), a department store chain operating primarily in the Southern and Western U.S., holds a significant net cash position of $803.9 million, representing 8% of its market capitalization. Despite this financial stability, the company is currently
trading at $643.91 per share with a forward P/E of 18.8x. Analysts express hesitation regarding Dillard's as an investment due to several performance indicators. The absence of new store openings suggests weak demand, with management reportedly focusing on improving existing locations rather than expanding. Furthermore, the company has experienced poor same-store sales performance over the past two years, indicating challenges in attracting new shoppers to its brick-and-mortar stores. Over the last three years, Dillard's profitability has also declined, with earnings per share dropping by 6.4% annually, a rate worse than its revenue performance.
Why It's Important?
The situation at Dillard's highlights a broader challenge within the retail sector, particularly for traditional department stores. While a strong cash position typically signals financial health, in Dillard's case, it may also indicate a reluctance or inability to invest in growth and adapt to evolving consumer preferences. The declining same-store sales and profitability suggest that the company is struggling to maintain market share and attract new customers in a competitive retail landscape increasingly dominated by e-commerce and specialized retailers. This trend could lead to further erosion of its customer base and financial performance if not addressed. For investors, the high forward P/E ratio combined with stagnating growth and declining profitability raises concerns about the stock's valuation and future potential. The company's focus on existing locations rather than expansion could be a strategic move to consolidate operations, but it also risks limiting future revenue growth in a dynamic market.
What's Next?
Dillard's will likely continue its strategy of focusing on optimizing the performance of its existing store locations. The company may explore various initiatives to improve same-store sales, such as enhancing the in-store customer experience, refining merchandise assortments, or implementing targeted marketing campaigns. Given the reported decline in earnings per share, management will need to identify and address the underlying factors contributing to reduced profitability. This could involve cost-cutting measures, supply chain efficiencies, or adjustments to pricing strategies. Investors will be closely watching for any signs of improved sales trends, increased profitability, or strategic shifts that could signal a turnaround. The company's substantial cash reserves provide a buffer, but sustained underperformance could eventually lead to pressure from shareholders for more aggressive growth strategies or capital allocation decisions.
Beyond the Headlines
The challenges faced by Dillard's reflect a significant shift in consumer behavior and the retail industry's structural changes. The rise of online shopping and the preference for experiential retail or specialized boutiques have put immense pressure on traditional department stores. Dillard's situation underscores the difficulty for established retailers to innovate and remain relevant in a rapidly changing market. The company's strong cash position, while seemingly positive, could also be interpreted as a missed opportunity if not strategically deployed for modernization, technological integration, or new market penetration. This scenario raises questions about the long-term viability of traditional department store models and the need for fundamental transformations to survive and thrive in the modern retail environment. The ethical implication for management is to balance short-term financial stability with long-term strategic investments for sustainable growth.