
What's Happening?
Oil prices experienced a dip in early Asian trade, driven by increasing expectations of improved global supplies, even as tensions persist in the Middle East. Brent oil futures for January delivery fell by 0.4% to $95.45 a barrel, continuing a two-session
decline. The International Energy Agency (IEA) recently reported that global oil markets are projected to return to a surplus in the fourth quarter of 2026. This forecast is based on a faster recovery in Middle East exports, despite ongoing shipping disruptions. The IEA also announced plans to release an additional 71 million barrels from its members' emergency reserves by the end of February. The agency now forecasts daily oil supplies of 105 million barrels in the fourth quarter, exceeding the daily forecast demand by approximately 1.7 million barrels per day. This revised outlook contrasts with the IEA's previous projection of a supply deficit for the same period.
Why It's Important?
The decline in oil prices, fueled by an improved supply outlook, has significant implications for the U.S. economy and consumers. Lower crude oil costs typically translate to reduced prices at the pump, offering relief to American households and businesses facing inflationary pressures. This could stimulate consumer spending and reduce operational costs for industries such as transportation and logistics. For U.S. energy policy, a global supply surplus might lessen the immediate pressure to increase domestic production, potentially influencing investment decisions in the oil and gas sector. While consumers benefit from lower prices, domestic oil producers might face reduced profitability. The IEA's revised forecast suggests a more stable global oil market in the near term, which could impact long-term energy strategies and trade balances for the United States.
What's Next?
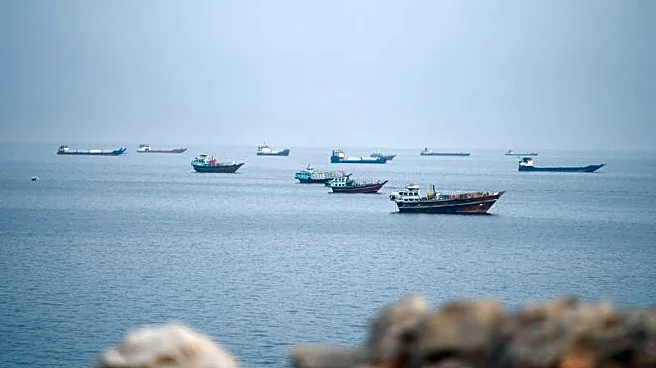
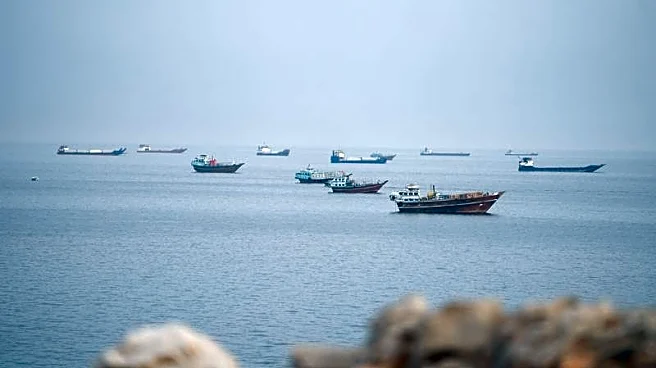
The oil market will continue to monitor the balance between recovering global supplies and persistent geopolitical tensions in the Middle East. While the International Energy Agency (IEA) projects a supply surplus, any escalation in U.S.-Iran tensions or disruptions in key shipping routes like the Strait of Hormuz could quickly shift market sentiment and prices. Investors will be watching for further reports on Middle East export recovery and the actual impact of the IEA's emergency reserve releases. The Organization of Petroleum Exporting Countries and allies (OPEC+) production levels, which reached 41.23 million barrels per day in October, will also remain a key factor. Future reports from the IEA and OPEC+ will provide crucial insights into the evolving supply-demand dynamics and potential price movements in the coming months.
Beyond the Headlines
The current market dynamics highlight a complex interplay between fundamental supply-demand forces and geopolitical risks. The IEA's revised outlook, signaling a return to surplus, suggests a resilience in global oil production and export capabilities, even amidst regional conflicts. This could lead to a re-evaluation of energy security strategies in the U.S., potentially shifting focus from immediate supply concerns to long-term energy transition goals. However, the continued high tensions between the U.S. and Iran, including reported strikes on military bases and tanker incidents, underscore the fragility of the situation. While the market is currently absorbing these shocks, the underlying instability could trigger rapid price spikes if a significant supply disruption were to occur. This scenario emphasizes the ongoing need for diversified energy sources and robust international diplomatic efforts to ensure global energy stability.