

What's Happening?
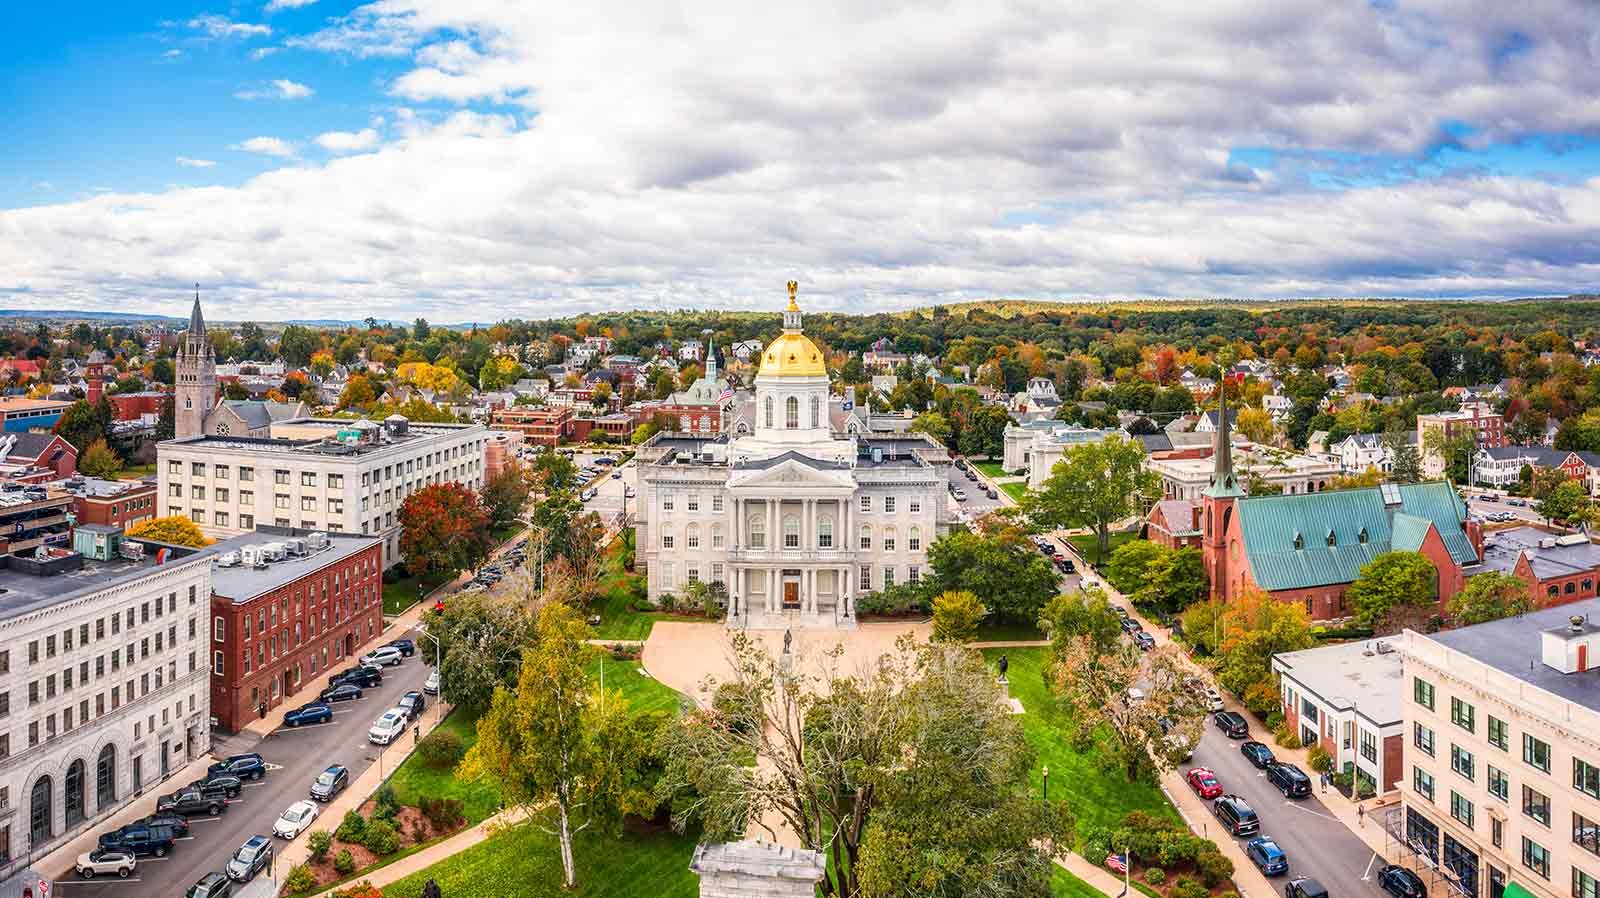
New Hampshire's state revenue collections in September showed a substantial surplus, primarily driven by unexpectedly strong business tax receipts. Combined General and Education Trust Funds revenues generated a cash surplus of $69.1 million for the month,
surpassing planned amounts by 21.0%. This surplus was largely due to Business Profits Tax (BPT) and Business Enterprise Tax (BET) receipts, which were $69.4 million (34.6%) above the State Revenue Plan forecast and $94.7 million (54.1%) higher than the previous year. While other revenue sources like Liquor Commission profits and Motor Fuels Tax revenue were below target, and interest earnings declined, these shortfalls were minor compared to the surge in business taxes. September is a critical month for business tax payments, as most are made through quarterly estimated tax payments. This overperformance significantly impacted the state's finances, reversing a previous deficit in combined business tax revenues for State Fiscal Year (SFY) 2027 to a $63.0 million (24.7%) surplus year-to-date.
Why It's Important?
The significant surplus in New Hampshire's business tax revenue has immediate and long-term implications for the state's fiscal health and policy decisions. The unexpected boost provides greater financial flexibility, potentially influencing discussions around the next State Budget. This surge in revenue, particularly from BPT and BET, suggests a stronger-than-anticipated economic performance among businesses within the state, or at least a more aggressive catch-up in tax payments. The report notes that national corporate profits increased substantially, and large multi-state and multi-national filers, which constitute a significant portion of New Hampshire's tax base, likely contributed to this rise. This trend could indicate a more robust business environment, potentially leading to increased state investments in public services or tax relief measures. Conversely, if the increase is primarily due to businesses adjusting underpayments from earlier in the year, it might not signal a sustained economic boom, necessitating careful consideration by policymakers.
What's Next?
Policymakers will closely monitor revenue trends, particularly the next major quarterly estimate payment in December, to determine if September's surge indicates a sustained trend or a one-off adjustment. The Governor's revenue projections, expected in February, will be crucial in shaping the upcoming State Budget discussions. The report highlights that the causes of the increase are not fully clear, as the Department of Revenue Administration does not receive detailed explanations from taxpayers for changes in estimated payments. Factors such as declining refunds, businesses under-forecasting profits earlier in the year, and a potential return to pre-policy change trendlines are considered possible contributors. The state will need more data to ascertain the longevity of this positive revenue performance and its implications for future fiscal planning. The rise in corporate tax revenues is also noted as not unique to New Hampshire, suggesting broader economic factors may be at play.
Beyond the Headlines
The substantial increase in New Hampshire's business tax revenue, while positive, also brings to light deeper considerations regarding tax policy and economic forecasting. The report mentions that New Hampshire's business tax revenues remain lower than in the years immediately following the COVID-19 pandemic, even with this recent uptick. Furthermore, it points out that various tax policy changes, such as caps on credit carryforwards and lower business tax rates, likely resulted in significant forgone revenue for the state in previous years. The analysis suggests that while BPT revenue grew, lower BPT rates did not yield a detectable benefit to the New Hampshire economy, and reductions in the BET rate were followed by reduced BET revenue. This raises questions about the effectiveness of past tax policies in stimulating economic growth versus simply reducing state income. The current surplus offers an opportunity for policymakers to re-evaluate these policies and their long-term impact on both state finances and the broader economy, ensuring that future tax strategies are both fiscally sound and genuinely beneficial for economic development.