


What's Happening?
DoorDash announced robust financial results for fiscal Q3 2026, ending September 30, reporting a 34.0% year-over-year increase in revenue to $4.62 billion. The company also achieved an expanded operating margin of 9.6%, up from 7.5% in the prior year,
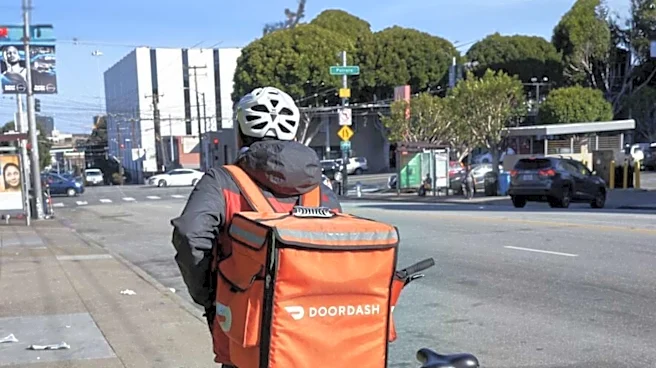
setting new records for both revenue and net income. Concurrently, DoorDash agreed to acquire the online grocery platform Instacart for approximately $17 billion in equity value, with at least 75% of the payment in cash. This acquisition news initially boosted DoorDash's stock by 5.6% on October 29, though it closed flat the following day. Despite these positive developments, DoorDash's stock experienced a 25.2% decline for investors between October 30, 2025, and November 2, 2026, underperforming the S&P 500's 11.8% return. However, the stock has shown a partial recovery, gaining 10.1% from May 4 to November 2, 2026. Additionally, DoorDash has initiated a new offering of $12 meal deals in several cities, featuring full meals from local restaurants with no delivery fees.
Why It's Important?
The strong Q3 performance and the strategic acquisition of Instacart signal DoorDash's aggressive expansion and diversification efforts within the competitive delivery market. The Instacart acquisition, valued at $17 billion, positions DoorDash to significantly enhance its footprint in the online grocery sector, potentially creating a dominant force in the broader on-demand delivery industry. This move could intensify competition with rivals like Uber Eats and traditional grocery chains expanding their delivery services. The introduction of $12 meal deals with no delivery fees is a direct response to consumer demand for value and affordability, aiming to attract new customers and increase order frequency, especially in a market sensitive to economic pressures. While the stock has seen a significant year-over-year decline, the recent recovery and strategic initiatives suggest DoorDash is actively working to regain investor confidence and secure long-term growth. The company's ability to integrate Instacart and successfully scale its new meal deals will be crucial for its future market position and profitability.
What's Next?
DoorDash is expected to report its fiscal Q4 2026 results in February 2027, with analysts closely monitoring its operating margin for continued improvement. The integration of Instacart will be a key focus, as DoorDash navigates the complexities of merging two large-scale delivery platforms and realizing the anticipated synergies. The success of the $12 meal deals will also be evaluated, as DoorDash aims to assess their impact on customer acquisition, retention, and overall revenue. Competitors in the food and grocery delivery space are likely to respond with their own strategic initiatives, potentially leading to further price wars or service innovations. Investors will be watching how DoorDash manages its valuation, which currently stands at 4.8 times its sales over the past twelve months, compared to the S&P 500's 3.3 times. The company's ability to sustain its growth trajectory while effectively integrating its new acquisition and expanding its value offerings will be critical in the coming quarters.
Beyond the Headlines
The acquisition of Instacart by DoorDash represents a significant consolidation in the on-demand delivery sector, potentially reshaping the landscape of how consumers access prepared meals and groceries. This move could lead to increased market power for DoorDash, raising questions about potential impacts on merchant fees, delivery worker compensation, and consumer choice in the long term. The introduction of fixed-price meal deals also highlights a broader industry trend towards value-driven offerings, reflecting evolving consumer spending habits in a fluctuating economic environment. This strategy could put pressure on smaller restaurants and delivery services to compete on price, potentially affecting their profitability and market share. Furthermore, the deal underscores the ongoing convergence of food delivery and grocery delivery services, suggesting a future where a single platform could cater to a wider range of consumer needs, thereby increasing convenience but also potentially reducing competition. The ethical implications of such market dominance, particularly concerning data privacy and algorithmic fairness for both consumers and delivery workers, may become more prominent as DoorDash expands its reach.