

What's Happening?
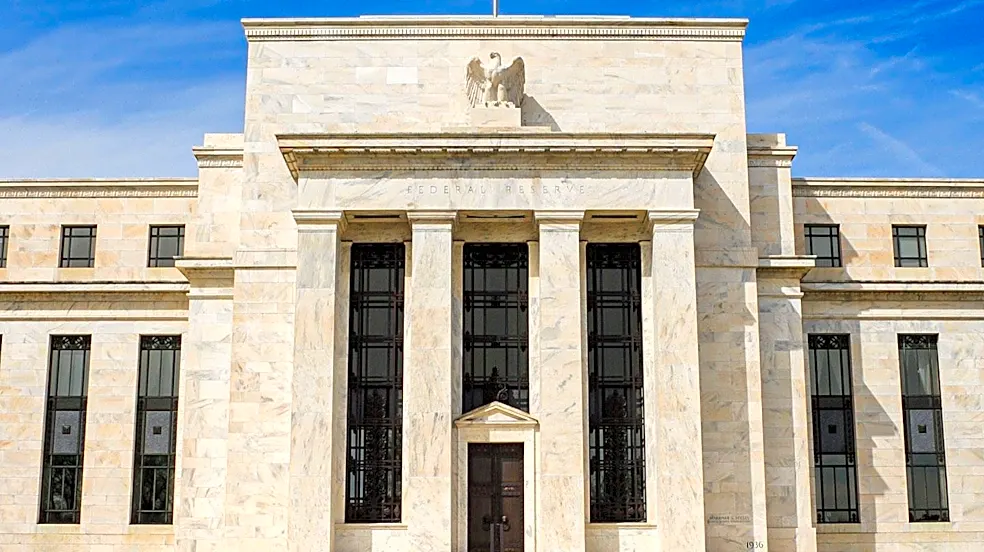
Contrary to common belief, mortgage rates are not solely determined by the Federal Reserve's actions. While the Fed sets short-term interest rates like the federal funds rate, mortgage rates are more closely linked to the 10-year U.S. Treasury bond. This
bond serves as a primary indicator for mortgage pricing, with lenders adding a margin to cover their costs and risks. Several other factors significantly influence mortgage rates, including inflation expectations, global investment trends, and the demand for Mortgage-Backed Securities (MBS). When investors anticipate inflation, they demand higher yields on bonds, which in turn pushes mortgage rates up. Global events can also drive investors to or from U.S. bonds, affecting yields. Furthermore, the Fed's reduction in MBS purchases means less demand and higher rates, as investors seek greater returns.
Why It's Important?
Understanding the true drivers of mortgage rates is crucial for potential homebuyers and the broader housing market. A common misconception that mortgage rates directly follow Fed rate changes can lead to misguided decisions, such as waiting for the Fed to lower rates, which may not translate into lower mortgage costs. This can result in missed opportunities to purchase a home or build equity. The influence of the 10-year Treasury yield, inflation expectations, and global market dynamics means that mortgage rates can fluctuate independently of the Fed's short-term rate adjustments. For lenders, risk assessment in the housing market and adherence to strict regulations also play a role in setting rates, sometimes preventing them from passing on savings even if the Fed lowers its rates. This complex interplay of factors necessitates a more nuanced approach to understanding and predicting mortgage rate movements.
What's Next?
Given that mortgage rates are influenced by a multitude of factors beyond the Federal Reserve, prospective homebuyers should focus on their personal financial situation rather than solely on Fed announcements. Instead of attempting to time the market, individuals are advised to consider if they can afford current payments, if a home purchase aligns with their long-term equity building goals, and if it represents a smart investment. Lenders are offering various tools to help navigate higher rates, such as rate buydown programs, assistance with closing costs, and adjustable-rate mortgages with lower initial rates. The prevailing advice is to 'marry the house, date the rate,' meaning to purchase the right home when available and consider refinancing later if rates decrease. This strategy emphasizes securing a suitable property and building equity, rather than delaying a purchase based on uncertain future rate movements.
Beyond the Headlines
The evolving landscape of mortgage rates reflects a fundamental shift in how financial markets operate in the post-2008 era. The Fed's role in the housing market, particularly its past purchases of MBS, has created a complex environment where its withdrawal from such activities directly impacts rates. This highlights the interconnectedness of monetary policy, global finance, and individual consumer decisions. The emphasis on factors like inflation expectations and global investment trends underscores the increasing influence of broader economic forces on everyday financial products. This situation also brings to light the importance of financial literacy for consumers, empowering them to make informed decisions by looking beyond simplistic interpretations of economic news. The housing market is no longer solely a domestic affair but is deeply intertwined with international capital flows and investor sentiment, making it a more dynamic and less predictable environment.