

What's Happening?
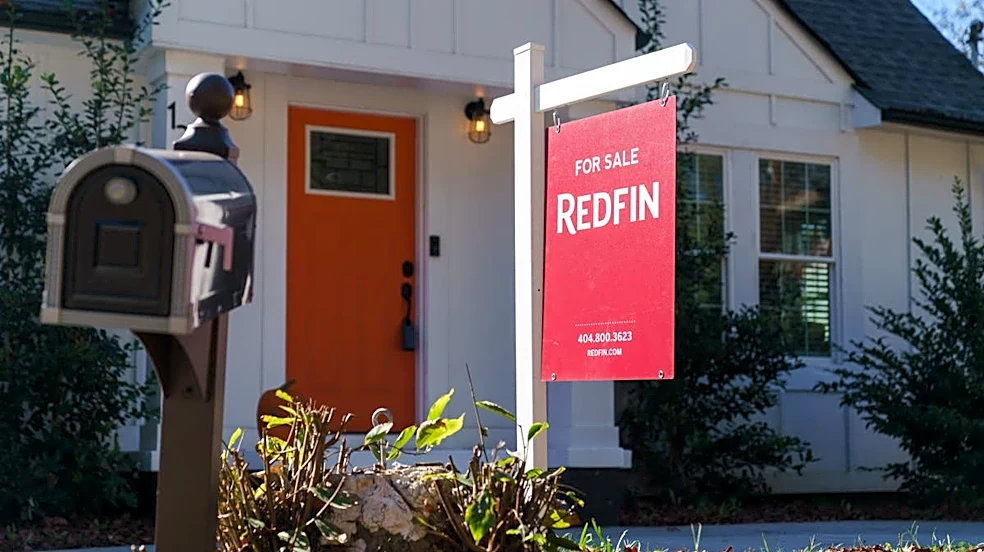
New residential construction in the U.S. experienced a significant decline in September, reaching one of its weakest paces since the pandemic began. Housing starts decreased by 5.2% to an annualized rate of 1.22 million, falling below all economist estimates
in a Bloomberg survey. Single-family home starts dropped to their lowest level in a year, and permit applications for these dwellings, a key indicator of future construction, also fell to their lowest point since early 2023. This downturn is largely attributed to affordability challenges exacerbated by higher mortgage rates, which are deterring potential homebuyers and impacting homebuilder confidence, now at a 14-year low. New construction on multifamily projects also saw a nearly 7% decrease.
Why It's Important?
This decline in housing starts is a critical indicator for the U.S. economy, signaling a slowdown in a sector that significantly contributes to GDP. The reduced construction activity directly impacts numerous industries, including building materials, labor, and financial services. Higher mortgage rates are making homeownership less accessible for many Americans, leading to decreased demand and a backlog of unsold homes. This situation can stifle economic growth, as sluggish home construction has already weighed on the economy in five of the last six quarters. The Federal Reserve Bank of Atlanta's GDPNow forecast, which projected a decline in residential investment, further underscores the economic concerns. A sustained downturn in housing could lead to job losses in construction and related fields, and potentially impact consumer spending and overall economic stability.
What's Next?
The housing market is expected to continue facing headwinds as long as mortgage rates remain elevated and affordability challenges persist. Homebuilders may further reduce their construction plans until existing inventories are absorbed and buyer confidence improves. Policymakers and financial institutions will closely monitor these trends for potential interventions or adjustments to monetary policy. The upcoming months will likely reveal whether this slowdown is a temporary correction or a more prolonged contraction in the housing sector. Consumers will continue to face a challenging environment for home purchases, potentially leading to increased demand for rental properties or a delay in homeownership aspirations.
Beyond the Headlines
Beyond the immediate economic figures, the housing market's struggles highlight deeper societal implications. The increasing unaffordability of homes, driven by high interest rates and persistent inflation, exacerbates wealth inequality and limits opportunities for many Americans to build equity. This trend can have long-term effects on household financial stability and intergenerational wealth transfer. The decline in single-family home construction, in particular, points to a shift in housing availability and potentially a greater reliance on multifamily units. This could reshape urban planning, community development, and the American dream of homeownership. The situation also underscores the delicate balance between controlling inflation through interest rate hikes and the unintended consequences on vital economic sectors like housing.