
What's Happening?
U.S. Customs and Border Protection (CBP) has issued an interim final rule, 'Heightened Requirements for Foreign Importers of Record,' effective January 5, 2027. This rule, published on November 6, 2026,
in the Federal Register, implements Section 2 of Executive Order (E.O.) 14411, 'Strengthening Customs Enforcement.' The new regulations introduce two significant changes. First, foreign Importers of Record (IORs) will only be permitted to enter goods into the U.S. if they are validated under the Customs Trade Partnership Against Terrorism (CTPAT) program or utilize a CTPAT-validated customs broker. Second, the definition of a 'U.S. IOR' is now more stringent, requiring businesses to be located in the U.S., organized under U.S. law, and meet specific ownership or real property criteria. Specifically, at least 51% of beneficial owners with control must be U.S. citizens or lawful permanent residents, or the entity must directly own a significant amount of unencumbered U.S. real property. U.S. subsidiaries of foreign parents may not qualify as U.S. IORs based on ownership alone unless they meet the real property alternative. An IOR is the entity responsible for making entry, paying duties, and fulfilling U.S. import requirements.
Why It's Important?
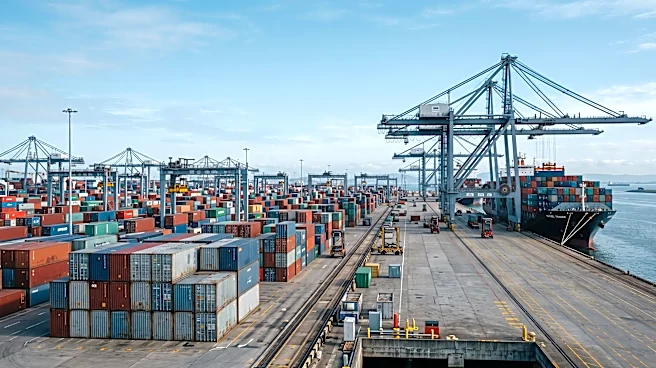
These new CBP regulations are poised to significantly impact international trade and supply chains involving the U.S. The stricter requirements for foreign IORs aim to enhance customs enforcement and address issues such as unpaid duties, which CBP reports amount to $1.01 billion from non-CTPAT foreign IORs since October 1, 2020. The rule will likely lead to increased scrutiny during importer onboarding processes, with brokers requiring detailed ownership charts, financial statements, and proof of U.S. assets. Many foreign IORs may need to switch to CTPAT-validated brokers, potentially straining the capacity of the 643 active CTPAT-validated brokers compared to the 2,428 non-validated ones. Foreign-owned U.S. subsidiaries that do not meet the new U.S. IOR criteria will be treated as foreign IORs, subjecting them to the same requirements. Companies operating under Delivered Duty Paid (DDP) sales models, where foreign sellers act as IORs, will face the full impact, potentially shifting IOR responsibilities to U.S. customers who must also meet the U.S. IOR test. Inaccurate U.S. IOR declarations could result in goods being held at ports until duties are paid, creating cash flow and supply chain risks, especially with existing tariffs.
What's Next?
Importers must take proactive steps before the January 5, 2027, effective date. This includes evaluating the ownership and asset structure of each importing entity to determine its U.S. IOR qualification. Companies should confirm their customs broker's CTPAT validation status, map beneficial ownership up to natural persons, and assess tax and transfer pricing implications if considering establishing or restructuring a U.S. entity. It is crucial to test each existing U.S. entity against the new 19 CFR 110.2 criteria, including the six verification factors, and document the conclusions. Importers also need to decide how each entity will answer the U.S. IOR declaration and agree on this approach with their broker. Reviewing Incoterms, distribution agreements, and customer contracts to establish importer responsibilities is also essential. Modeling the cash flow impact if live entry is required and considering the implications of owning or leasing real property for U.S. entities are further necessary steps. Public comments on the interim final rule are due by January 5, 2027, and CBP may revise the rule after this period, so monitoring for updates is important.
Beyond the Headlines
The new CBP rule signifies a broader shift towards enhanced supply chain security and accountability in U.S. import operations. By mandating CTPAT validation or the use of CTPAT-validated brokers for foreign IORs, the U.S. is leveraging a program designed to strengthen international supply chains against terrorism and other illicit activities. This move could incentivize more foreign entities to join CTPAT, thereby improving overall global trade security. The stricter definition of a U.S. IOR also reflects a push to ensure that entities responsible for imports have a substantial and verifiable presence within the U.S., making enforcement of customs laws more effective. This could lead to a restructuring of international business operations, with foreign companies potentially needing to establish more robust U.S. presences or re-evaluate their import strategies. The rule also highlights the increasing complexity of international trade compliance, placing a greater burden on importers and customs brokers to ensure accuracy and adherence to evolving regulations. The potential for increased penalties and audit exposure for entry errors underscores the need for meticulous compliance and due diligence in every import transaction.