

What's Happening?
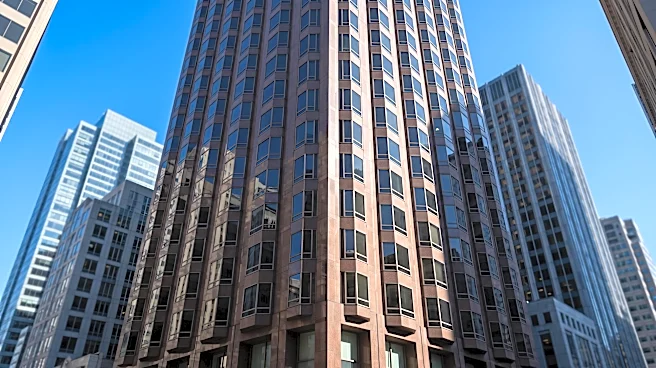
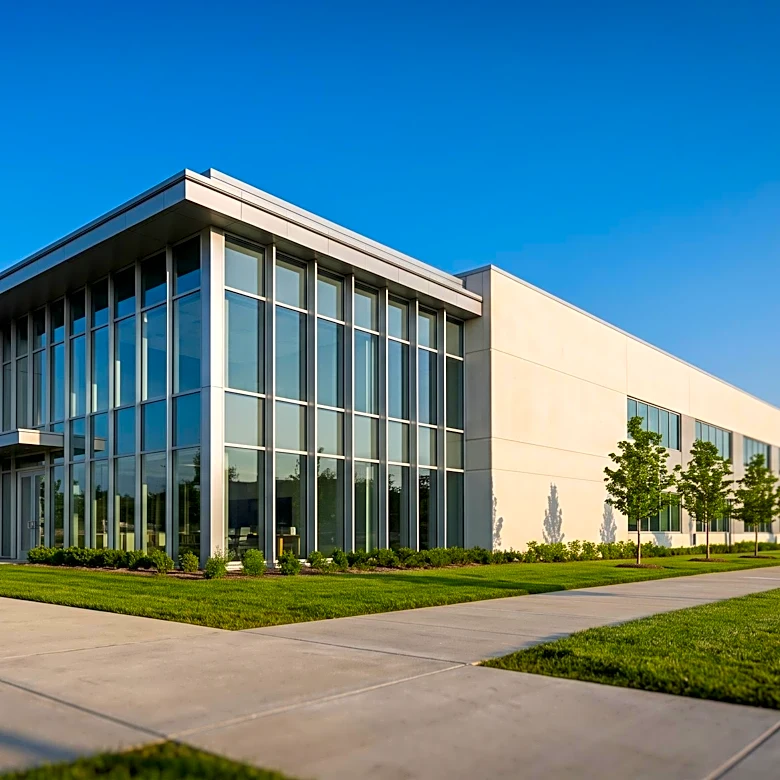
A new report from CBRE indicates a significant shift in Canada's office market, favoring landlords in lease negotiations. This change is driven by strong demand and a slowdown in new supply. Net absorption of office space across the country totaled two
million square feet in the third quarter of this year, with nine out of eleven regional markets experiencing positive net leasing activity. Notably, there were no significant office project completions during this period, and full-year new supply is projected to be 2.3 million square feet, considerably below the recent five-year average. New inventory is expected to remain constrained beyond 2027, with conversions and demolitions further reducing available office space in cities like Toronto, London, and Ottawa. Marc Meehan, CBRE Canada research managing director, stated that the office recovery trend is now "well-entrenched," creating a landlord's market, particularly for limited "trophy" building spaces. This competition is extending to other property classes, with increased leasing velocity in areas neighboring downtown cores, especially in Toronto. Eight Canadian markets, including Toronto, Calgary, Ottawa, and Halifax, reported declining downtown vacancy, while Vancouver saw an increase due to consolidation by a single tech tenant. National sublease space also decreased by 1.3 million square feet, the largest quarterly decline since 2005, signaling improved occupier sentiment.
Why It's Important?
This shift to a landlord's market in Canadian office space has significant implications for businesses and the broader economy. Companies seeking premium office locations will face increased competition and potentially higher leasing costs, impacting their operational budgets and location strategies. The scarcity of new supply, coupled with ongoing conversions and demolitions, means that businesses may struggle to access quality office space in desirable areas, potentially hindering expansion plans or forcing them into less optimal locations. This situation could particularly affect growing industries that rely on prime office real estate. The improved occupier sentiment, as indicated by the reduction in sublease space, suggests a renewed confidence in physical office environments, which could further intensify demand. For real estate investors and developers, the constrained supply and high demand present opportunities for increased rental income and property value appreciation, especially for existing "trophy" buildings. However, the long lead times for new construction, with significant completions not expected until 2032 or later, highlight a potential bottleneck for future economic growth and urban development.
What's Next?
The current market dynamics suggest that businesses in Canada should anticipate continued challenges in securing desirable office space and prepare for potentially higher leasing costs. Companies may need to explore alternative strategies, such as pre-leasing future developments, considering secondary markets, or optimizing their existing footprints to mitigate the impact of limited supply. For developers, the strong demand and constrained supply create a favorable environment for new office projects, although the long construction timelines mean that any new supply will not alleviate current pressures for several years. The focus on "trophy" buildings and prime locations will likely intensify, leading to further competition for these assets. The trend of declining downtown vacancy in most major Canadian cities is expected to persist, with the exception of outliers like Vancouver, which may see continued adjustments due to specific tenant movements. The ongoing reduction in sublease space indicates a sustained commitment to physical office presence, suggesting that hybrid work models are not entirely negating the need for traditional office environments. Stakeholders will closely monitor construction starts and economic indicators to gauge any shifts in this landlord-favored market.
Beyond the Headlines
The evolving Canadian office market reflects broader post-pandemic trends and challenges in urban planning and economic development. The strong return to office, particularly for premium spaces, underscores the enduring value of physical collaboration and corporate identity, even in an era of remote and hybrid work. This situation raises questions about the long-term sustainability of urban centers if businesses are priced out or unable to find suitable space. It also highlights the critical role of timely infrastructure and real estate development in supporting economic growth. The scarcity of new supply, partly due to increased construction costs and regulatory hurdles, could exacerbate existing inequalities, making it harder for smaller businesses or startups to establish a presence in prime locations. Furthermore, the conversion of office spaces to other uses, while addressing some urban needs, contributes to the reduction of available office inventory, creating a complex interplay of supply and demand across different property types. This scenario could lead to a re-evaluation of urban planning policies to ensure a balanced and accessible commercial real estate market that supports diverse business needs.