

What's Happening?
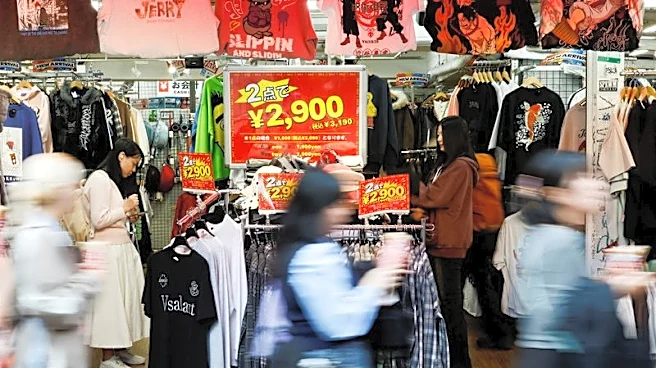
Japan's economy experienced an unexpected contraction in the third quarter, with its Gross Domestic Product (GDP) falling an annualized 0.1% quarter-over-quarter. This decline marks the first in four quarters and is attributed to rising living costs that
have compelled households to reduce spending. Private consumption, a significant component of economic output, decreased by 0.3%. Persistent price pressures, exacerbated by factors such as Middle East tensions and unfavorable weather conditions, including heavy rain and typhoons, negatively impacted household spending. Demand for automobiles and air conditioners also saw a retreat after a temporary boost in the previous quarter due to tax and regulatory changes. Despite this contraction, capital spending, driven by investments in labor-saving technologies and AI-related projects, rose by 1.6%. Net external demand, representing exports minus imports, detracted 0.6 percentage points from growth, largely due to a sharp increase in imports of oil and other energy purchases.
Why It's Important?
The unexpected economic contraction in Japan highlights the vulnerability of households to persistent inflation, even in an environment of rising wages. This situation underscores a broader economic challenge where wage growth, while present, is insufficient to offset the impact of increasing prices on consumer purchasing power. For the U.S. and global markets, Japan's economic performance can serve as an indicator of how developed economies are navigating inflationary pressures. A weakened Japanese economy could impact global supply chains and demand for goods and services, potentially affecting U.S. businesses with international operations or investments. The Bank of Japan's (BOJ) response to this data, particularly regarding its interest rate policy, will be closely watched, as it could influence global monetary policy trends and investor sentiment. The emphasis on AI-related investments in capital spending also points to a global trend of technological adoption as a driver of economic activity, even amidst broader economic headwinds.
What's Next?
Policymakers in Japan are expected to closely monitor the economic situation, though some economists suggest that the current weakness may not deter the Bank of Japan (BOJ) from its tightening path. The BOJ has already implemented interest rate hikes in June and September, and many analysts anticipate another hike as early as December, driven by stubbornly high energy costs and rising import prices from a weak yen. However, if consumer spending continues to weaken, it could lead to differing opinions among BOJ board members, with some potentially advocating for a more cautious approach to further rate increases. The Japanese government expects a gradual economic recovery, supported by improvements in employment and income, as well as various policy measures. Nevertheless, the impact of the Middle East situation on energy prices and global trade will remain a critical factor to monitor. Longer-term, Japan faces challenges to its growth, with projections indicating it could slip to the world's sixth-largest economy by 2027.
Beyond the Headlines
The economic contraction in Japan, despite rising wages, reveals a critical disconnect between nominal wage growth and real purchasing power, a phenomenon that could have broader implications for other developed economies, including the U.S. This situation highlights the complex interplay between inflation, consumer behavior, and monetary policy. The reliance on capital spending, particularly in AI and labor-saving technologies, as a counter-balance to weak consumer demand, suggests a structural shift in economic drivers. This could lead to increased productivity in certain sectors but may not immediately translate into widespread consumer relief if inflation persists. The ongoing debate within the BOJ regarding interest rate hikes in the face of fragile private consumption underscores the ethical and policy dilemma central banks face: balancing inflation control with economic growth and household well-being. This scenario could prompt a re-evaluation of traditional economic indicators and policy responses in an era of persistent global inflationary pressures.