
What's Happening?
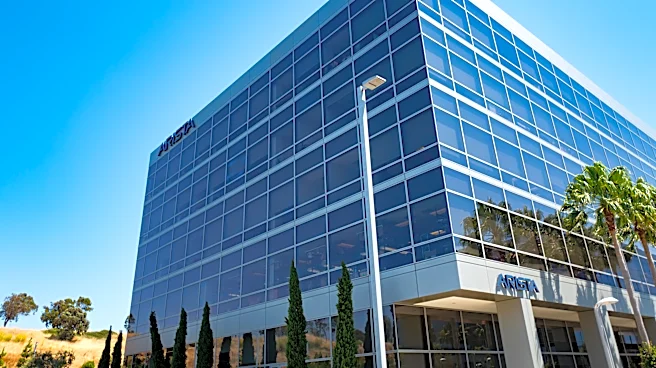
Arista Networks is a dominant provider of high-performance networking platforms essential for managing data traffic in large data centers and cloud environments. The company specializes in high-speed switching for cloud titans and providers developing
artificial intelligence clusters. In the 12 months ending September 30, 2026, Arista Networks reported revenue of nearly $11.9 billion, marking a robust growth rate of approximately 40.7% over the previous year. Net income for the same period was close to $4.8 billion, demonstrating a net margin of roughly 40%. The company's financial health is further underscored by a debt-to-equity ratio of 0.0x as of its December 2025 balance sheet, a current ratio of approximately 3.0x, and free cash flow of nearly $4.3 billion in fiscal year 2025. However, the company faces customer concentration risk, with two specific customers accounting for 16% and 26% of its revenue.
Why It's Important?
Arista Networks' strong financial performance and market leadership are crucial indicators of the escalating demand for high-speed infrastructure driven by cloud computing and artificial intelligence. The company's ability to achieve significant revenue growth and maintain high net margins highlights the profitability and scalability of its software-driven model. Its robust balance sheet, characterized by zero debt and substantial free cash flow, provides financial stability and flexibility for future investments and operations. This makes Arista a key enabler of the digital transformation across various industries. However, the concentration of revenue from a few major customers introduces a notable risk factor, as any changes in their spending patterns could significantly impact Arista's financial outlook.
What's Next?
Arista Networks is expected to continue its growth trajectory as the demand for high-speed networking infrastructure for cloud and AI systems intensifies. The company's focus on specialized switching for AI clusters positions it well to capitalize on the ongoing expansion of artificial intelligence capabilities across various sectors. Future performance will largely depend on its ability to maintain strong relationships with its major customers while potentially diversifying its client base to mitigate concentration risks. Additionally, Arista will need to navigate competition from established rivals like Cisco and Hewlett Packard Enterprise, as well as emerging competitors like Nvidia, and manage its reliance on Broadcom as a sole source for switching chips. Geopolitical tensions and trade restrictions could also impact its supply chain and revenue patterns.
Beyond the Headlines
Arista Networks' success reflects a broader trend in the technology sector where foundational infrastructure providers are becoming increasingly critical to the digital economy. The company's high net margins and strong free cash flow underscore the value placed on specialized, high-performance networking solutions. The customer concentration issue, while a risk, also highlights the significant influence and scale of major cloud and AI players in shaping the technology landscape. This dynamic suggests that strategic partnerships and customer retention will remain paramount for infrastructure providers. Furthermore, Arista's reliance on a single supplier for critical components points to potential vulnerabilities in the global supply chain, a recurring theme in the tech industry that could lead to strategic shifts in sourcing and manufacturing in the long term.