


What's Happening?
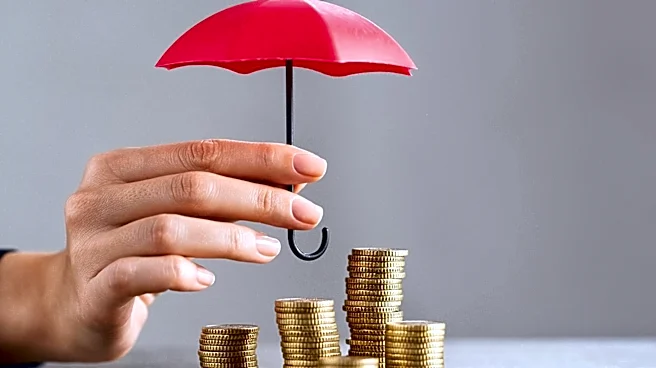
Umbrella insurance policies provide an additional layer of liability coverage that extends beyond the limits of standard homeowners and auto insurance policies. In a society where civil lawsuits are common, these policies are designed to protect individuals
from significant financial losses in the event of a major claim or lawsuit. For example, if a homeowner's policy has a liability limit of $300,000, an umbrella policy can add an extra $1 million in coverage, bringing the total protection to $1.3 million for incidents like someone being injured on their property. Similarly, an umbrella policy supplements auto liability coverage. The primary home or auto policy pays first, and the umbrella policy covers any excess costs once those underlying limits are exhausted. Daniel Halsey, President of The Hanover's Personal Insurance, emphasizes that even individuals who do not consider themselves wealthy need to protect all their assets, including current and future wages, retirement savings, business income, and college funds, as these are at risk without umbrella protection in most states.
Why It's Important?
The importance of umbrella insurance in the U.S. stems from the litigious nature of society and the potential for substantial financial judgments. Standard liability limits on home and auto policies may not be sufficient to cover the costs of severe accidents, injuries, or other unforeseen events that lead to lawsuits. Without umbrella coverage, individuals could face the loss of personal assets, including savings, property, and future earnings, to satisfy a judgment that exceeds their primary insurance limits. This type of policy offers peace of mind by safeguarding a family's financial future against catastrophic liability claims. With policies offering $1 million in coverage starting at a relatively low cost, financial experts often recommend it as a high-value investment for asset protection. Raising deductibles on primary policies can sometimes even offset the cost of an umbrella policy, making it an accessible option for many.
What's Next?
Individuals are encouraged to consult with local independent insurance agents to customize an umbrella policy that aligns with their specific needs and asset protection goals. This involves reviewing existing home and auto insurance liability limits and determining the appropriate level of additional coverage. As personal assets grow or life circumstances change, such as purchasing new property or increasing net worth, the need for higher umbrella coverage should be re-evaluated. The ongoing trend of civil litigation suggests that the demand for comprehensive liability protection will continue, making umbrella policies an increasingly standard component of personal financial planning. Insurers will likely continue to offer flexible options to integrate umbrella coverage with existing policies, simplifying the process for consumers to enhance their overall protection.
Beyond the Headlines
Beyond direct financial protection, umbrella insurance reflects a broader societal concern about personal liability and risk management in an increasingly interconnected world. The policy's coverage for libel, slander, defamation, invasion of privacy, wrongful entry, and wrongful eviction highlights the expanding scope of potential liabilities individuals face, not just from physical accidents but also from digital interactions and social media. This suggests a growing awareness among insurers and consumers of the legal ramifications of online activities and personal conduct. The relatively low cost for significant coverage also points to the actuarial understanding that while severe liability events are rare, their impact can be devastating. Therefore, umbrella policies serve as a collective risk-sharing mechanism that provides critical security for individuals against unforeseen, high-impact events, fostering greater financial stability and reducing the long-term societal costs associated with personal bankruptcies due to liability judgments.