


What's Happening?
Texas Instruments Incorporated (NASDAQ: TXN) has reported third-quarter results that surpassed consensus expectations, with revenue reaching approximately $6.06 billion, marking a 27.7% year-over-year increase. Earnings per share (EPS) stood at $2.62,
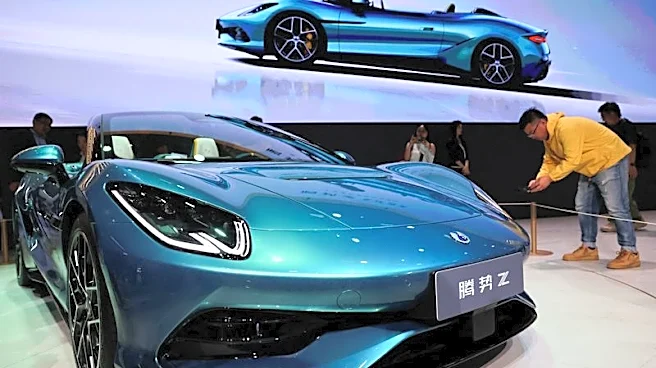
exceeding the $2.40 consensus estimate. The semiconductor giant also provided an optimistic outlook for the fourth quarter, projecting revenue between $5.80 billion and $6.30 billion and EPS ranging from $2.45 to $2.79. This strong performance is partly attributed to a rebound in China's automotive demand, particularly in electric vehicles, which has increased the analog content per car. The company also announced a dividend increase, raising its quarterly payout to $1.52 per share from $1.42, resulting in an annualized dividend of $6.08 and a yield of approximately 1.9%. Institutional investors hold a significant 84.99% of the company's stock, with firms like ProShare Advisors LLC and Bank of New York Mellon Corp increasing their stakes.
Why It's Important?
Texas Instruments' performance is often viewed as a key indicator for the broader industrial and automotive electronics sectors due to its extensive customer base and diverse product portfolio, which includes chips for power management, signal conversion, and motor control. The positive results suggest a potential turning point for the semiconductor industry, especially concerning automotive demand, which has been a significant growth driver. The increased dividend signals confidence from management in the company's financial health and future cash flow generation, making it an attractive option for income-focused investors. The substantial institutional ownership underscores the market's belief in Texas Instruments' long-term prospects, despite some analyst caution regarding its valuation. The company's strategic investment in large-wafer fabs is also crucial, as it aims to secure market share by ensuring reliable supply to customers as demand cycles shift.
What's Next?
Investors will be closely watching Texas Instruments' fourth-quarter and full-year earnings release, typically issued in late January, for further insights into market trends and the company's strategic direction. In the interim, industry data, such as monthly semiconductor sales reports from industry associations, and statements from key customers in the automotive and industrial sectors will provide additional context. Releases from competitors like Analog Devices and Microchip Technology will also be important to determine if the observed market improvements are company-specific or indicative of a broader industry recovery. The company's continued investment in manufacturing capacity, supported by initiatives like the federal CHIPS and Science Act, will be a key factor in its ability to meet future demand and maintain its competitive edge. The balance between capital expenditure and free cash flow distribution will also remain a focus for shareholders.
Beyond the Headlines
The strong performance of Texas Instruments highlights the increasing importance of semiconductor content in modern vehicles, particularly electric vehicles, which require advanced chips for battery management, power conversion, and driver assistance systems. This trend suggests a sustained demand for analog and embedded processing chips, positioning Texas Instruments favorably in the long term. The company's strategy of building capacity ahead of demand, while capital-intensive, aims to create a competitive advantage by ensuring supply chain resilience and customer loyalty. However, potential risks include the impact of global economic slowdowns on industrial demand and the growing competition from Chinese analog suppliers, who are expanding with state support. The ongoing debate about the justification of TXN's elevated earnings multiple against future free cash flow, especially with heavy investments in manufacturing, will continue to influence investor sentiment and analyst ratings.