
What's Happening?
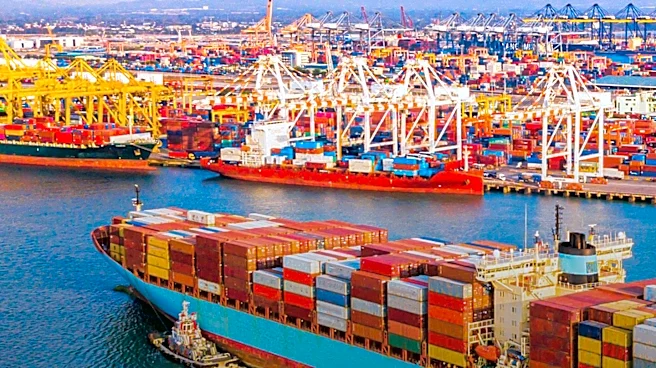
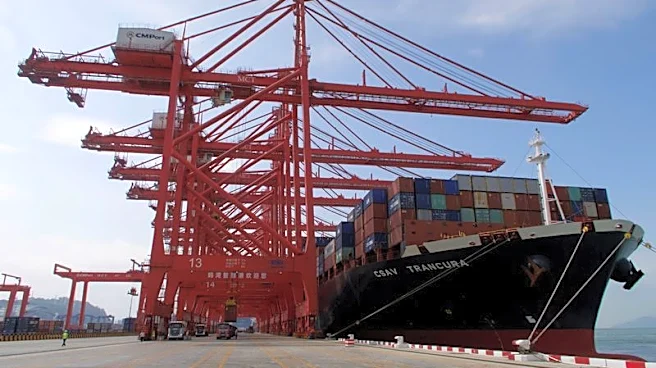
U.S. container imports are projected to decrease through the end of 2026, following a peak shipping season that spanned from May to mid-October. This forecast comes from the Global Port Tracker report, a joint publication by the National Retail Federation
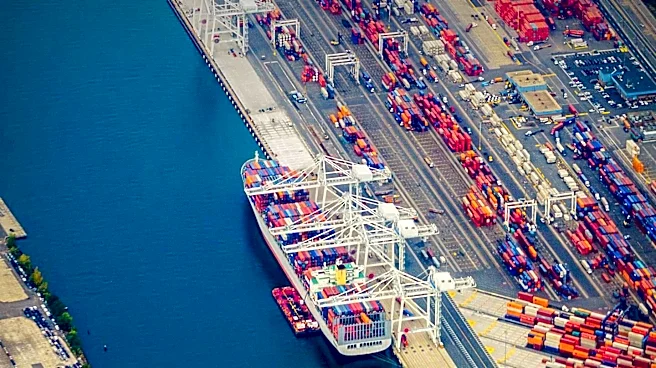
and Hackett Associates. The surge in imports, which began in May, was initially triggered by tariffs introduced in the second quarter and sustained by consumer spending despite rising inflation. However, these high volumes have led to significant backups at several U.S. ports, particularly on the West Coast, where cargo has experienced extended delays awaiting transfer to rail cars. A potential strike by watchmen at Los Angeles and Long Beach ports was averted in early November through a short-term contract extension between International Longshore and Warehouse Union Local 26 and the Pacific Maritime Association, though a long-term agreement remains elusive.
Why It's Important?
The anticipated slowdown in U.S. container imports and ongoing port delays carry significant implications for the national economy and various industries. For retailers, while most holiday merchandise has already arrived, continued delays could impact restocking efforts and the availability of goods in early 2027. Supply chain disruptions, particularly on the West Coast, can lead to increased shipping costs and longer lead times for businesses, potentially affecting consumer prices and corporate profitability. Industries reliant on imported components or finished goods, such as electronics, apparel, and automotive, could face operational challenges. The situation also highlights the fragility of the U.S. supply chain infrastructure and the need for improved logistics and port efficiency. The unresolved long-term contract between the ILWU Local 26 and the Pacific Maritime Association introduces ongoing uncertainty, posing a risk of future labor disputes that could further exacerbate port congestion and economic instability.
What's Next?
As U.S. container imports are expected to slow, the focus will likely shift to clearing existing backlogs at ports, especially on the West Coast. Stakeholders will be closely monitoring the progress of cargo transfers to rail cars and overall port efficiency. The ongoing contract negotiations between the International Longshore and Warehouse Union Local 26 and the Pacific Maritime Association will remain a critical point of attention, as a long-term agreement is essential to prevent future disruptions. Businesses may continue to adjust their supply chain strategies, potentially diversifying port usage or increasing inventory levels to mitigate the impact of future delays. Policymakers may also face renewed pressure to invest in port infrastructure and logistics improvements to enhance the resilience of the national supply chain. The coming months will reveal how effectively ports and logistics networks can adapt to these challenges and whether the slowdown in imports helps alleviate current congestion.
Beyond the Headlines
The recurring issues of port congestion and supply chain disruptions in the U.S. point to deeper systemic challenges beyond immediate import volumes. These include underinvestment in infrastructure, labor relations complexities, and the increasing demands of a globalized economy. The reliance on a few major ports, particularly on the West Coast, creates choke points that are vulnerable to various disruptions, from labor disputes to surges in demand. This situation could accelerate a broader re-evaluation of U.S. trade routes and logistics strategies, potentially leading to increased investment in East Coast and Gulf Coast ports, or even a push towards nearshoring or reshoring manufacturing to reduce reliance on overseas shipping. Furthermore, the interplay between tariffs, consumer spending, and supply chain capacity highlights the intricate connections within the global economy, where policy decisions can have far-reaching and sometimes unintended consequences on the flow of goods and economic stability.