

What's Happening?
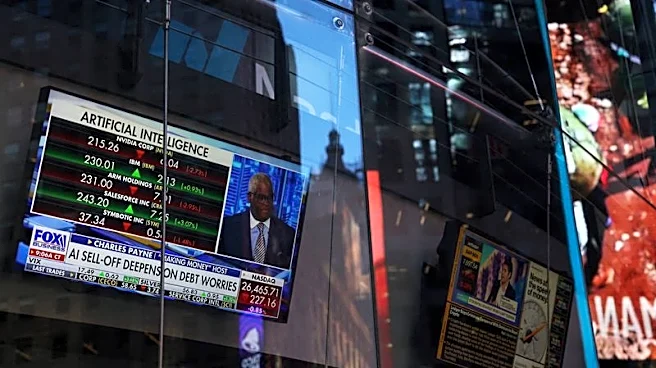
The U.S. stock market has experienced a significant narrowing of leadership, with AI-related stocks disproportionately driving headline returns. The S&P 500 has risen much faster than its median constituent, and only a minority of stocks have outperformed
the index. Breadth measures, such as the number of stocks trading above their 50-day moving average and the cumulative advance-decline line, indicate a divergence from overall market performance. For instance, while the S&P 500 was up over 13% year-to-date, the median constituent was up only about 5.6%. A small group of 20 names, predominantly in technology (13 of which are tech, 3 healthcare, 3 energy), were up over 100% year-to-date, representing only 6% of the index. This concentrated performance has led to active equity managers who are underweight the AI trade lagging their benchmarks, impacting overall model performance. In response, some investment models have rebalanced by exiting indirect AI exposures, such as industrial renaissance and global metals ETFs, and establishing direct positions in technology (XLK) and semiconductor (SOXQ) ETFs to account for sector exposures among underlying active equity managers.
Why It's Important?
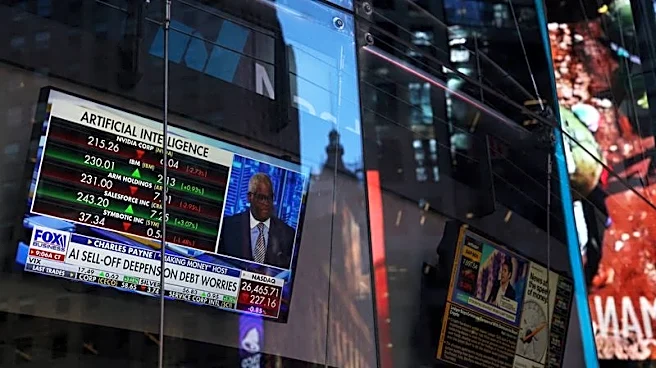
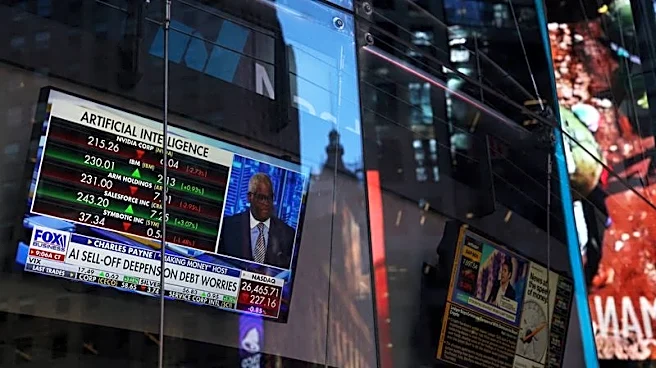
The narrow market leadership driven by AI has significant implications for portfolio management and investment strategy. The high dispersion in returns means that getting exposure to the winning AI-related sectors is crucial, while missing out can lead to substantial underperformance. With AI and AI-themed derivatives estimated to constitute almost 60% of the market, being underexposed to this theme can easily leave investors behind. This environment has increased the volatility of relative performance for diversified portfolios, prompting a more hands-on approach to managing sector underweights. The shift towards direct AI exposure through technology and semiconductor ETFs reflects a recognition that indirect plays are no longer as efficient. Furthermore, the market is becoming more discerning about the financing of AI infrastructure, with borrowing costs rising for weaker credits and those with less clarity in revenue streams. This could lead to a slowdown in the CapEx cycle, potentially softening growth and inflation impulses, which could be beneficial for bonds and might eventually lead to a broader market participation beyond the immediate AI leaders.
What's Next?
The market is showing signs of a potential shift in dynamics regarding AI investment. While the AI buildout is expected to have a long runway, the funding for this CapEx is becoming more selective. The market is no longer willing to issue blank checks, and borrowing is being allocated more distinctly, with weaker credits facing higher costs. This discernment could slow down the overall CapEx cycle, which in turn might soften growth and inflation impulses, potentially leading to lower interest rates. Lower rates could then allow for a pivot away from the concentrated AI trade into broader market segments, particularly for well-capitalized large-cap companies. However, small-cap companies might continue to struggle due to higher financing costs. Investors are likely to prioritize quality, focusing on companies with strong cash flow, such as hyperscalers, while being cautious of less well-capitalized AI participants. This nuanced view suggests a potential broadening of leadership within the large-cap space, benefiting ignored S&P 500 names that have been overlooked during the AI speculative rush, as concerns about rising interest rates subside.