

What's Happening?
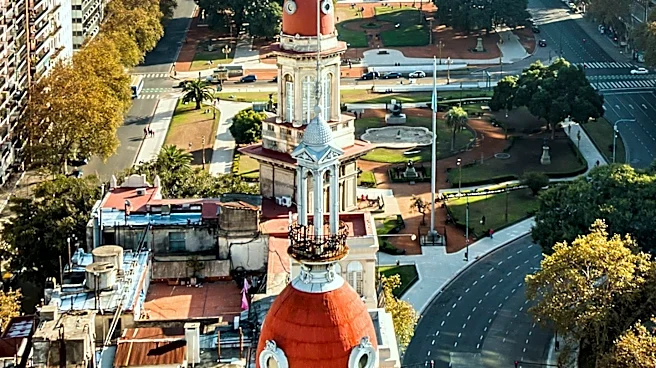
Argentina has officially committed to joining the Crypto-Asset Reporting Framework (CARF) promoted by the Organisation for Economic Co-operation and Development (OECD). This makes Argentina the 77th jurisdiction to participate in this international mechanism
aimed at integrating crypto-assets into the cross-border tax information exchange system. Under this arrangement, Argentina is required to establish its legal and technical systems by September 2029. Following this implementation, the country will begin the automatic exchange of crypto-transaction data with other participating jurisdictions. The primary goal of CARF is to assist tax authorities in identifying crypto-asset activities that occur outside a taxpayer’s country of residence. Crypto-asset service providers covered by this framework will be mandated to collect customer identity and transaction information, including names, addresses, tax residency status, taxpayer identification numbers, and relevant transaction data. This information will then be shared with the tax authority of the customer's tax residency for verification of their tax filings. It is important to note that this framework does not introduce new cryptocurrency taxes; rather, it provides tax authorities with more comprehensive information to ensure the completeness and accuracy of existing tax obligations.
Why It's Important?
Argentina's decision to join the OECD's CARF signifies a significant step towards greater transparency and regulation within the global cryptocurrency market. For the U.S., this move contributes to a broader international effort to combat tax evasion and illicit financial activities facilitated by crypto-assets. As more countries adopt such frameworks, it creates a more standardized and interconnected system for tracking crypto transactions, which can indirectly benefit U.S. tax authorities in their efforts to monitor cross-border financial flows involving American citizens or entities. The increased data exchange can help prevent individuals from using international crypto platforms to avoid U.S. tax obligations. Furthermore, this commitment reflects a global trend towards integrating digital assets into traditional financial regulatory structures, potentially influencing future U.S. policy decisions regarding cryptocurrency taxation and reporting requirements. While not directly impacting U.S. tax laws, the precedent set by Argentina and other nations in adopting CARF could accelerate similar discussions and implementations within the U.S., aiming to level the playing field for tax compliance across different asset classes.
What's Next?
Argentina is now tasked with developing and implementing the necessary legal and technical infrastructure to support the CARF by September 2029. This will involve establishing domestic rules that mandate crypto-asset service providers to collect and report customer and transaction data. The OECD Global Forum on Tax Transparency and Exchange of Information will continue to monitor Argentina's progress and implementation, as it does with all member jurisdictions. Once fully operational, Argentina will commence the automatic exchange of crypto-transaction data with other CARF-participating countries. This will enable tax authorities globally to receive comprehensive information on cross-border crypto activities, enhancing their ability to verify tax filings. The move is also expected to further integrate digital asset services into mainstream banking applications within Argentina, albeit under a more clearly defined tax reporting system. The success of Argentina's implementation could serve as a model or influence other nations considering joining the CARF, further expanding the global network of crypto tax information exchange.
Beyond the Headlines
Argentina's embrace of the CARF highlights a growing global consensus on the need for greater oversight in the rapidly evolving crypto-asset space. This development underscores a fundamental shift in how governments perceive and regulate digital currencies, moving from a hands-off approach to one of integration and accountability within existing financial frameworks. The ethical implications revolve around balancing financial privacy with the imperative of preventing tax evasion and illicit financing. While the framework aims to enhance transparency, it also raises questions about data security and the potential for misuse of sensitive financial information. Culturally, this move signifies the increasing mainstream acceptance of cryptocurrencies, but also their formalization within traditional economic systems, potentially altering the decentralized ethos often associated with digital assets. Long-term, this could lead to a more harmonized global regulatory environment for cryptocurrencies, fostering greater stability and legitimacy for the asset class, but also potentially increasing compliance burdens for users and service providers worldwide.