
What's Happening?
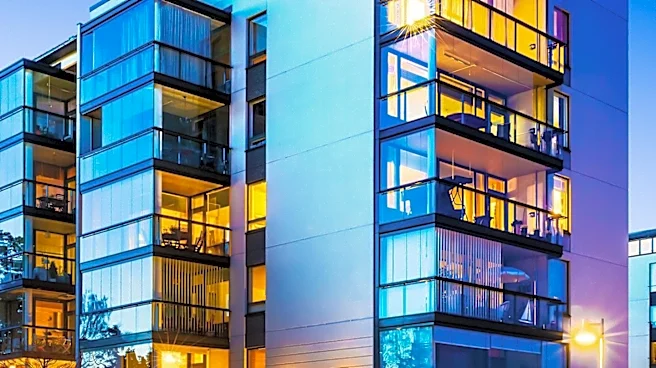
Government-sponsored enterprises (GSEs) like Fannie Mae and Freddie Mac are leading the growth in the U.S. multifamily mortgage market. According to a report by the Mortgage Bankers Association (MBA), the GSEs' share of outstanding multifamily mortgage debt
increased to 50.0 percent at the end of Q2, marking a 0.1 percentage point rise from the previous quarter. Their holdings reached $1,168 billion, an increase of $12.66 billion. This growth signifies that GSEs not only hold the largest share of outstanding multifamily mortgage debt but also contributed the most to the net increase in Q2, accounting for 61.2 percent of the total increase. Other significant holders of multifamily debt include banks and thrifts, which increased their holdings to $667.6 billion, and life insurance companies, whose direct holdings rose by $4.23 billion to $268.5 billion. State and local governments maintained their holdings at $99.22 billion. The total multifamily mortgage debt outstanding in Q2 rose by $20.69 billion, reaching $2.338 trillion, and represented 46.2 percent of all commercial mortgage debt.
Why It's Important?
The dominant role of government-sponsored enterprises in the multifamily mortgage market has significant implications for housing affordability and stability in the U.S. Their substantial investment helps ensure a consistent flow of capital into the multifamily sector, which is crucial for the development and maintenance of rental housing. This stability can indirectly impact rental prices and availability, affecting a large segment of the U.S. population. The continued growth in GSE holdings suggests a reliance on government-backed entities to support this vital housing segment, potentially shielding it from some market volatilities but also raising questions about the extent of government involvement in the housing market. The call from lenders for greater alignment between federal mortgage programs (FHA, VA) and GSEs further underscores the interconnectedness of these entities and their collective impact on the broader mortgage landscape. This alignment could streamline processes, potentially making it easier for developers and property owners to secure financing, which in turn could influence housing supply and market dynamics.
What's Next?
The continued growth and influence of GSEs in the multifamily mortgage market suggest that their policies and lending practices will remain critical determinants of the sector's health. Lenders are advocating for increased alignment between federal mortgage programs, such as those offered by the FHA and VA, and the GSEs. This push for streamlining could lead to policy discussions aimed at harmonizing regulations and operational procedures across these government-backed entities. Such changes could simplify the mortgage application process for multifamily properties, potentially encouraging more investment and development in the sector. Stakeholders, including real estate developers, property managers, and financial institutions, will likely monitor these developments closely, as any shifts in GSE or federal program policies could impact their access to capital, financing costs, and overall market strategies. The Mortgage Bankers Association, representing the real estate finance industry, will likely continue to play a key role in advocating for these changes.
Beyond the Headlines
The increasing dominance of government-sponsored enterprises in the multifamily mortgage market highlights a broader trend of public sector involvement in critical economic sectors. While GSEs provide stability and liquidity, their significant market share also raises questions about potential moral hazard and the balance between public support and private market competition. The concentration of debt within these entities could create systemic risks if not properly managed, as their financial health is closely tied to the overall housing market. Furthermore, the call for greater alignment between various federal mortgage programs and GSEs points to an ongoing effort to optimize government intervention in housing finance. This optimization could lead to a more integrated and potentially more efficient system, but it also necessitates careful consideration of how such integration might affect market diversity, innovation, and the equitable distribution of housing resources across different demographics and regions in the U.S.