

What's Happening?
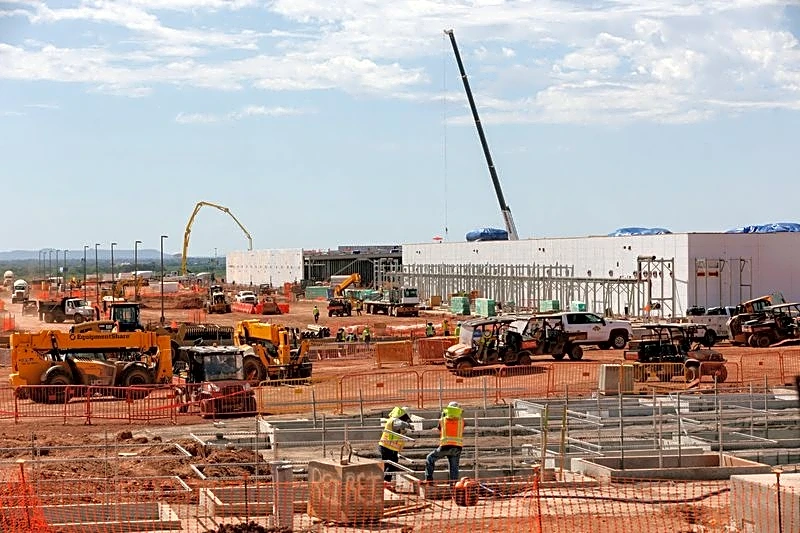
Warehouse landlords are experiencing a surge in demand, leading to rent increases and strong financial performance for several Real Estate Investment Trusts (REITs). This trend is driven by three primary factors: the continued growth of e-commerce, the reshoring
of advanced manufacturing to the U.S., and companies needing more space as they deplete lean inventories. EastGroup Properties reported a 7.9% year-over-year increase in Funds From Operations (FFO) to $2.45 per diluted share in Q3, raising its quarterly dividend by 12.9% to $1.75. Prologis saw Core FFO rise 7.4% to $1.60 per diluted share, with occupancy at 95.6% and new leases signed at a 38.0% net effective rent increase. First Industrial Realty Trust reported a 52% increase in cash rents on new and renewal leases, with cash same-store Net Operating Income (NOI) growing 5.6%. Rexford Industrial Realty, focused on Southern California, reported a GAAP net loss due to a non-cash write-down but maintained a high occupancy of 95.7%.
Why It's Important?
The robust performance of warehouse REITs signifies a significant shift in the U.S. commercial real estate market, driven by fundamental changes in supply chains and consumer behavior. The sustained demand for industrial space, fueled by e-commerce expansion and the return of manufacturing, indicates a long-term structural tailwind for these companies. This trend supports dividend growth for investors, making these REITs attractive for income-focused portfolios. The ability of these landlords to raise rents and maintain high occupancy rates, even amidst broader economic uncertainties, highlights the essential nature of logistics and distribution infrastructure. Furthermore, the increasing integration of data centers within these portfolios, as seen with Prologis's 5.8 gigawatts of power in its data center pipeline, points to a convergence of industrial real estate with the burgeoning technology sector, creating new revenue streams and diversification opportunities.
What's Next?
Warehouse REITs are expected to continue benefiting from strong market fundamentals. EastGroup Properties has raised its full-year guidance to $9.62-$9.68 per share, indicating continued optimism. Prologis has significant embedded rent growth, with leases averaging 16% below current market rates, suggesting future NOI increases as leases roll over. First Industrial has already handled a large portion of its 2026 and 2027 lease expirations with substantial rent increases. However, risks remain, such as EastGroup's reliance on selling new shares for growth, Prologis's pending SEGRO combination, and First Industrial's slight dip in occupancy. Rexford Industrial's performance will be closely watched in its upcoming Q3 report, particularly regarding Southern California rent trends. The sector will also need to navigate potential interest rate changes and construction costs, which could impact development pipelines and profitability.
Beyond the Headlines
The booming warehouse sector reflects deeper economic and societal shifts. The 'Amazon effect' has fundamentally reshaped retail, making efficient logistics and last-mile delivery critical. The reshoring of manufacturing, often driven by geopolitical considerations and supply chain resilience, further solidifies the need for modern industrial facilities. This trend also has implications for labor markets, as demand for warehouse workers and logistics professionals increases. Environmentally, the growth of e-commerce and warehousing raises questions about sustainable logistics, energy consumption in large facilities, and the environmental impact of increased transportation. The integration of data centers into industrial portfolios also highlights the growing demand for digital infrastructure, blurring the lines between traditional real estate and technology assets, and potentially leading to new regulatory and infrastructure challenges.