


What's Happening?
The global copper market is experiencing a significant shift in its long-standing annual benchmark pricing system for treatment and refining charges (TC/RCs). Historically, a major miner, such as Chile's Antofagasta, would agree on terms with Chinese
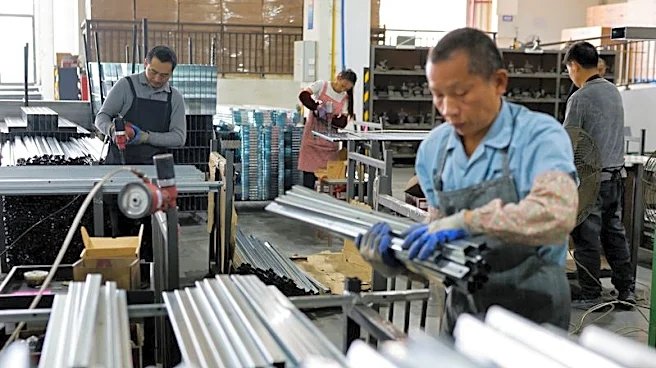
smelters, setting an annual benchmark for these fees that influenced long-term supply contracts worldwide. However, a severe shortage of copper concentrate, exacerbated by China's rapid smelter expansion outpacing mine development and recent mine outages, has led to a collapse in these fees. The benchmark, which was US$80 a tonne in 2024, dropped to US$21.25 in 2025, and is projected to be zero for 2026. In the spot market, treatment charges have gone 'well below zero,' meaning smelters are now paying miners for the privilege of processing their concentrate. For instance, Antofagasta recently sold a parcel from its Centinela mine at a negative US$310 a tonne treatment charge, and Teck reportedly sold material at minus US$370s.
Why It's Important?
This unprecedented situation signifies a major power shift in the copper supply chain, moving leverage from smelters to concentrate producers. Miners will receive higher effective prices for their copper, as negative treatment charges act as a bonus on top of the copper price, directly boosting their margins. This change is reminiscent of how the iron ore market transitioned from annual benchmarks to spot-indexed pricing. The shift could lead to increased volatility in miner earnings, though largely in their favor during periods of concentrate scarcity. Non-Chinese custom smelters, which rely on purchasing concentrate from other mines, face severe competitive pressure and potential closure, as Chinese smelters can leverage scale, by-product credits, and state support. This dynamic could reshape the global copper smelting landscape, concentrating more processing capacity in China.
What's Next?
Industry observers, including Ivanhoe Mines founder Robert Friedland, suggest there's a real possibility that no annual benchmark will be agreed upon for 2027. If this occurs, concentrate contracts would transition to rolling spot index pricing, fundamentally altering how copper concentrate is traded globally. The gap between miners' and smelters' expectations for the 2027 benchmark is at an all-time high, with miners pushing for deeply negative numbers. The shift towards spot-indexed sales has already begun, with Antofagasta agreeing to such terms with some Chinese smelters. This trend indicates a move away from decades-old practices, potentially leading to a more dynamic but also more volatile market for copper concentrate. The long-term viability of non-Chinese smelters will be a key concern, with some potentially requiring government intervention or facing closure.
Beyond the Headlines
The collapse of the copper concentrate benchmark highlights the critical importance of raw material supply in global industrial processes. This development underscores the strategic value of owning and controlling mining assets, particularly those producing high-quality concentrate. The increasing power of concentrate producers could incentivize further investment in mine development, potentially alleviating future supply shortages, but also raising questions about market concentration and pricing fairness. The situation also brings to light the environmental and economic implications of smelting capacity, as the closure of less competitive smelters outside China could have regional economic impacts and shift environmental responsibilities. The move to spot pricing could also introduce greater financial risk for market participants who are not adequately hedged against price fluctuations.