

What's Happening?
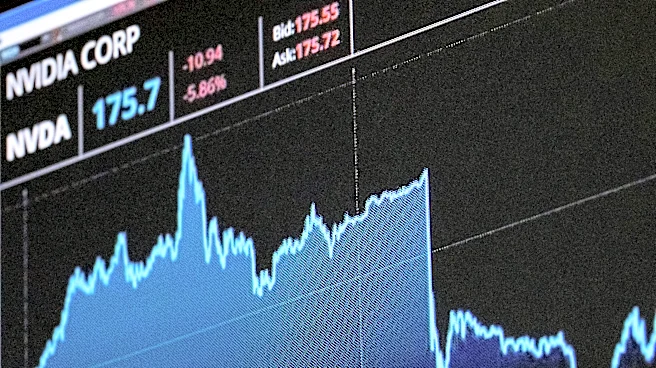
Citi has tactically revised its equity allocations, downgrading US equities, global technology, and European technology from Overweight to Neutral. This decision stems from concerns that investor positioning in these sectors could further deteriorate.
Concurrently, Citi has upgraded European equities, excluding the UK, to Overweight, citing the region's lower concentration of technology stocks and potential benefits from declining oil prices. The bank's move reflects a more cautious near-term assessment of technology stocks, influenced by recent market volatility and growing uncertainty surrounding artificial intelligence investment. While Citi maintains a positive medium-term outlook on AI, it seeks clearer evidence of stabilized market positioning and sentiment before re-establishing an Overweight call on AI-related investments. The bank noted that investor positioning in the Nasdaq is currently near neutral, but a further 5% decline could push investors into net-short territory, contributing to the decision to reduce technology exposure.
Why It's Important?
This strategic shift by a major financial institution like Citi carries significant implications for U.S. financial markets and technology companies. A downgrade from Overweight to Neutral suggests a potential cooling of investor enthusiasm and capital flow into these sectors, which have been primary drivers of market growth. For U.S. technology companies, this could translate into reduced investment, potentially impacting their valuations and growth trajectories. The move also highlights a broader reassessment of AI investment expectations and corporate earnings outlooks, indicating that the market may be entering a period of greater scrutiny for high-growth tech stocks. Investors in the U.S. may reallocate capital away from domestic tech, potentially seeking more stable or defensive assets, or exploring opportunities in other regions like Europe. This could lead to increased volatility in the U.S. tech sector and a broader market rebalancing, affecting retirement funds, institutional investments, and individual portfolios heavily weighted towards U.S. technology.
What's Next?
Citi will continue to monitor key market indicators, including investor positioning, credit spreads, and earnings expectations, to determine if conditions warrant further adjustments to its equity strategy. The bank has indicated that it will look for cleaner positioning and more stable AI sentiment, along with steady earnings per share revisions, before considering a return to an Overweight recommendation for AI-related investments. This suggests that the current neutral stance on U.S. equities and technology could persist until these conditions are met. Major stakeholders, including technology companies, investors, and financial analysts, will closely watch these metrics. Any sustained negative sentiment or further deterioration in earnings revisions could lead to prolonged pressure on U.S. tech stocks, while signs of stabilization or improvement might prompt a reversal of Citi's tactical downgrade. The upcoming U.S. midterm election results were also cited as a factor contributing to uncertainty regarding long-term AI expenditure, indicating that political developments could also influence future market sentiment.
Beyond the Headlines
The tactical downgrade by Citi, while focused on near-term market dynamics, hints at deeper shifts in investment philosophy and risk assessment within the financial industry. The emphasis on 'cleaner positioning' and 'stable AI sentiment' suggests a growing caution towards speculative investments and a demand for more tangible, consistent returns from technology and AI. This could signal a maturation of the AI investment cycle, moving from an initial phase of broad enthusiasm to a more discerning period where fundamental value and proven profitability become paramount. The shift also underscores the interconnectedness of global markets, as U.S. tech sentiment influences and is influenced by broader economic and geopolitical factors, including energy prices and regional economic performance. This could lead to a re-evaluation of diversification strategies, with a renewed focus on geographical and sectoral balance rather than concentrated bets on high-growth U.S. technology.