
What's Happening?
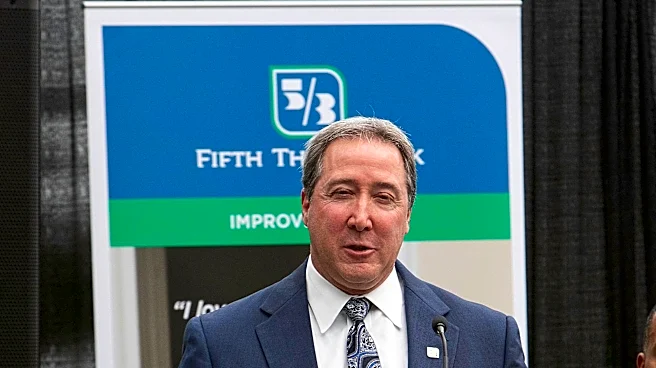
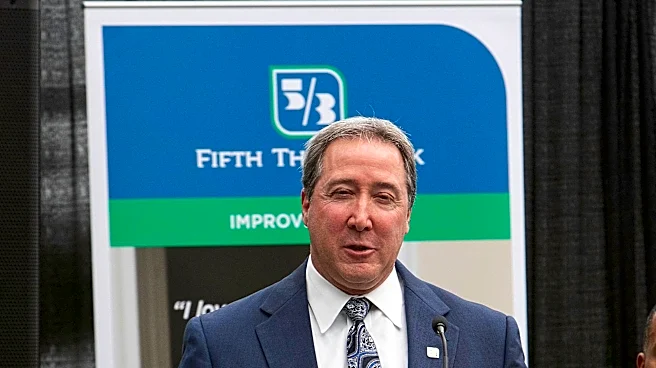
Fifth Third Bancorp reported stronger-than-anticipated adjusted earnings per share (EPS) and revenue for the third quarter of 2026. This positive financial performance was primarily attributed to the bank's stringent expense management and robust credit
quality. A significant factor contributing to these results is the ongoing integration of Comerica, which is expected to generate at least $850 million in annual expense synergies. Management has already completed a core conversion related to this integration, directly supporting the cost control measures that led to the earnings surprise. The bank's strategy focuses on a deposit-led model, leveraging the Comerica integration and technology investments to bolster earnings while mitigating credit risk. This quarter's results indicate that Fifth Third Bancorp is effectively aligning its asset risk and operating efficiency with its broader growth objectives, despite ongoing execution pressures in a competitive market.
Why It's Important?
This earnings beat is significant for Fifth Third Bancorp and its investors, as it validates the bank's strategic direction, particularly its ability to extract value from the Comerica integration. The successful implementation of expense synergies and maintenance of strong credit quality are crucial in a banking environment characterized by competitive and expensive deposit markets. Higher funding costs in such markets can erode net interest margins, making efficient cost control and resilient credit quality vital for profitability. For shareholders, the continued realization of Comerica savings and the avoidance of service disruptions, such as online banking glitches, are direct catalysts for sustained earnings growth. Conversely, any system issues or customer attrition stemming from the integration could quickly undermine these efficiency gains, making the integration a critical determinant of future performance.
What's Next?
Fifth Third Bancorp's immediate future will largely depend on its continued ability to efficiently integrate Comerica and expand its presence in the Southeast and Southwest regions. The bank aims to convert these initiatives into stable deposits and fee income while minimizing service disruptions. Analysts project Fifth Third Bancorp's earnings to reach approximately $4.3 billion by 2029, nearly doubling its current earnings of about $2.2 billion, with revenue expected to rise to around $16.4 billion by the same year, reflecting an annual growth rate of 17.7%. Achieving these projections hinges on the bank's capacity to maintain its expense discipline, avoid recurring technological issues, and retain low-cost deposits. The market will closely monitor how effectively the bank manages these operational aspects to sustain its positive earnings trajectory and realize the full benefits of the Comerica acquisition.
Beyond the Headlines
The successful integration of Comerica by Fifth Third Bancorp highlights a broader trend in the banking sector towards consolidation and efficiency-driven growth. In an increasingly competitive landscape, banks are seeking to enhance their market position and profitability through strategic acquisitions and technological advancements. The emphasis on expense synergies and core conversions reflects the industry's drive to optimize operational costs and leverage technology for improved efficiency. However, such large-scale integrations also present inherent risks, including potential service disruptions, customer attrition, and the complexities of merging disparate systems and cultures. Fifth Third Bancorp's performance will serve as a case study for how well financial institutions can navigate these challenges to achieve long-term growth and shareholder value in a dynamic economic environment.