




What's Happening?
Mortgage rates in the U.S. have decreased for the second consecutive week, providing some relief to prospective homebuyers. According to Freddie Mac's latest Primary Mortgage Market Survey, the average rate for a 30-year fixed mortgage fell to 7.24% for the week ending
October 29, down from 7.32% the previous week. The 15-year fixed mortgage rate also dropped to 6.60% from 6.68%. While this marks the lowest rates in over a month, they remain significantly higher than the 6.17% for a 30-year fixed rate recorded a year ago. Freddie Mac Chief Economist Sam Khater noted this as a positive development, modestly boosting purchasing power. However, housing economists caution that this improvement is relatively small compared to the substantial increase in borrowing costs experienced throughout the year, driven by inflation, energy prices, and Federal Reserve policy uncertainty. The 'mortgage rate lock-in effect' continues to limit housing supply as homeowners with lower rates are reluctant to sell.
Why It's Important?
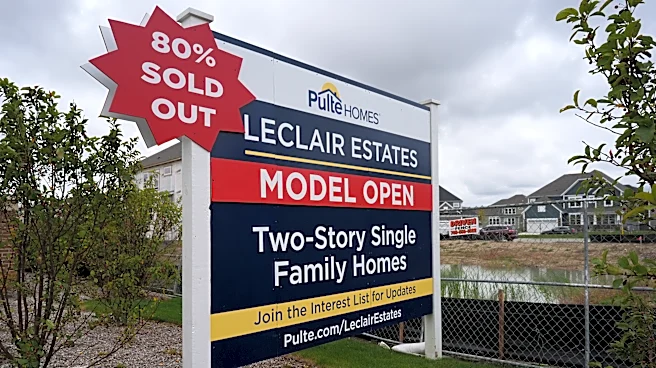
This modest decline in mortgage rates offers a glimmer of hope for U.S. homebuyers grappling with affordability challenges, but it underscores the persistent difficulties in the housing market. High rates, combined with limited inventory due to the 'lock-in effect,' continue to suppress buyer demand and keep home prices elevated in many communities. This situation creates a challenging environment for the housing industry, forcing homebuilders to rely on incentives like mortgage rate buydowns and price reductions to attract buyers. The volatility in rates, influenced by inflation and Federal Reserve actions, makes it difficult for both buyers and sellers to plan, contributing to market uncertainty. The ongoing affordability crisis disproportionately affects first-time buyers, hindering their ability to enter the housing market and build equity.
What's Next?
The future direction of U.S. mortgage rates will largely depend on inflation trends, Treasury market conditions, economic growth, and future Federal Reserve policy decisions. While the recent decline is positive, financial experts advise against assuming it signals a sustained downward trend, as rates can quickly reverse. Prospective homebuyers are encouraged to compare offers from multiple lenders, as rates can vary based on credit scores, down payments, and loan programs. Until borrowing costs experience a more significant and sustained decrease, affordability will likely remain a primary challenge for the U.S. housing market. The housing industry will continue to adapt through incentives and strategic pricing to navigate these conditions, while policymakers will monitor economic indicators for potential interventions.
Beyond the Headlines
The current state of the U.S. mortgage market reflects a complex interplay of economic forces that extend beyond simple supply and demand. The 'mortgage rate lock-in effect' is not just an economic phenomenon but also a psychological one, as homeowners weigh the financial benefits of their current low rates against the desire to move or upgrade. This creates a stagnant market where existing homes are not turning over, impacting mobility and potentially slowing economic growth in related sectors like home improvement and real estate services. Furthermore, the reliance on builder incentives highlights a market distortion where artificial inducements are needed to stimulate demand, rather than organic market forces. This situation could lead to long-term shifts in homeownership patterns and wealth accumulation, particularly for younger generations struggling to enter the market.