

What's Happening?
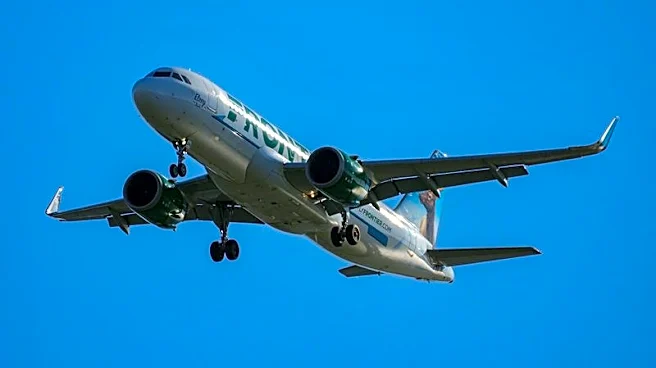
Frontier Group Holdings (ULCC) saw its stock price increase by 31.2% this week, closing at $6.48 on Thursday, October 29. This surge followed the ultra-low-cost carrier's announcement of record third-quarter revenue of $1.4 billion. The company also reported
adjusted earnings per share of $0.18, significantly surpassing Wall Street's estimates of a $0.06-per-share loss. Revenue for the third quarter was up 52.9% year-over-year, and revenue per available seat mile increased by 30%, driven by a passenger volume of 9.8 million. Despite a GAAP net loss of $104 million due to non-recurring fleet restructuring charges, the operational improvements and strong revenue growth fueled investor confidence.
Why It's Important?
This performance is significant for the U.S. airline industry, particularly for ultra-low-cost carriers. Frontier's ability to achieve record revenue and exceed profit estimates indicates a successful strategy in route restructuring and unit economics restoration, even amidst elevated fuel costs. The increase in passenger volume and revenue per available seat mile suggests a strong recovery in demand for budget air travel. This could set a precedent for other airlines in managing operational costs and optimizing routes. However, the company's substantial debt of $5 billion and an $817 million working-capital deficit highlight ongoing financial challenges that could impact its long-term stability and competitive position in the market.
What's Next?
Looking ahead to the fourth quarter of 2026, Frontier's management has guided for adjusted earnings per share between $(0.15) and $0.05. Elevated jet fuel prices are expected to remain a headwind, although unit revenue is projected to rise over 20% year-over-year. Investors will also be closely monitoring upcoming labor negotiations with pilots and flight attendants, which represent a critical operational cost factor over the next 12 to 24 months. The company's price-to-sales (P/S) ratio of 0.3, which is below the peer average, suggests that investors are cautious, and future earnings reports will be crucial in determining if the company can sustain its revenue growth and move towards consistent profitability.
Beyond the Headlines
Frontier's recent stock surge, while impressive, underscores a broader trend in the airline industry where carriers are navigating a complex environment of fluctuating fuel costs and evolving passenger demands. The company's strategy of unbundled base fares and charging separately for services is a key element of the ultra-low-cost model, allowing it to boost passenger traffic without sacrificing fare yields. However, the significant debt load and working-capital deficit raise questions about the long-term sustainability of this model, especially if unexpected operational disruptions occur. The success of Frontier's fleet restructuring and route adjustments could influence how other airlines approach their own operational strategies in a post-pandemic travel landscape.