
What's Happening?
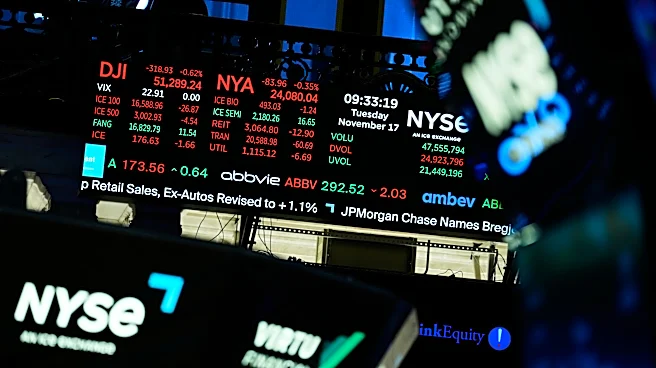
Morgan Stanley has announced a 15% increase in its quarterly dividend, raising it from $1.00 to $1.15 per share, effective with the payout declared on July 15, 2026. This move reflects the firm's successful pivot towards a wealth-management-led business
model, a strategy initiated after the 2008 financial crisis. Key to this transformation were the acquisitions of E*TRADE in 2020 and Eaton Vance in 2021, which significantly expanded its self-directed brokerage and asset management capabilities. As a result, client assets across Wealth and Investment Management reached $10.5 trillion in Q3 2026, surpassing the firm's $10 trillion target and marking an increase from $9.3 trillion at the end of 2025. CEO Ted Pick refers to this as the 'Integrated Firm strategy,' which has also seen strong performance in equity trading, with a 41% rise to $5.80 billion in Q3, and record revenue of $9.07 billion in Wealth Management. The firm's EPS of $3.03 also exceeded the consensus of $2.92.
Why It's Important?
This dividend increase signals Morgan Stanley's confidence in its strategic shift and its ability to generate sustainable income, primarily through its growing wealth management division. For investors, particularly those focused on income, the raised dividend enhances the attractiveness of Morgan Stanley's stock, offering a 2.54% yield based on a forward dividend of $4.60 per year. The firm's performance, which has seen a $1,000 investment a decade ago grow to approximately $6,022, significantly outperforming the S&P 500, underscores the success of its integrated approach. This strategy mitigates reliance on volatile investment banking revenues by building a more stable fee-based income stream. The continued growth in client assets and strong financial results demonstrate the effectiveness of integrating acquisitions like E*TRADE and Eaton Vance, positioning Morgan Stanley as a formidable player in the wealth management sector.
What's Next?
Morgan Stanley's 'Integrated Firm strategy' is expected to continue driving growth, with the bull case resting on wealth fees growing faster than any potential decline in trading revenue. The firm's ongoing multi-year $20 billion buyback program is also anticipated to provide further support for its stock price. However, potential challenges include the possibility of 2026 representing the peak of a market cycle, which could lead to a cooling in equity trading, particularly from Asia, and a continued decline in equity underwriting, which already fell 19% last quarter. Given the stock's beta of 1.22, it tends to move more significantly than the broader market during downturns. Nevertheless, for long-term income investors, the consistent growth in dividends and the increasing contribution of wealth management to the firm's revenue suggest a stable outlook.
Beyond the Headlines
The strategic transformation of Morgan Stanley from a traditional trading house to a wealth-management-led institution reflects a broader trend within the financial industry towards more stable, fee-based revenue models. This shift is driven by increased regulatory scrutiny on investment banking activities and the growing demand for wealth management services from an aging population and expanding affluent class. The successful integration of E*TRADE and Eaton Vance highlights the importance of strategic acquisitions in consolidating market share and diversifying service offerings. This approach not only enhances shareholder value through increased dividends and buybacks but also positions the firm to better withstand market volatility by relying on recurring revenue streams from client assets under management. The firm's ability to exceed its client asset targets demonstrates effective execution of its long-term vision.